
Basics for Financial Caregivers

November 21, 2016

If you’ve ever had to manage someone else’s money, you know it can be highly stressful. The responsibilities for managing a parent or other family member’s finances may have fallen on your shoulders suddenly or perhaps you had time to prepare to be a financial caretaker. It might be a responsibility you don’t even want or feel equipped to handle. Here are some resources to learn more about what your responsibilities entail and where you can turn for help.

What it means to be a fiduciary

Whether you have a power of attorney for finances or are a court-appointed guardian, a trustee, or a government fiduciary, you are required to act in the best interest of the person whose money you are managing. That’s called being a “fiduciary,” and it comes from the Latin word, “fiducia,” meaning trust. A fiduciary must act for the benefit of another person in a financial relationship and not for their own personal gain. The four basic duties of a fiduciary for a parent (or other person) are:

  • Act in your parent’s best interest;
  • Manage your parent’s money and property carefully;
  • Keep your parent’s money and property separate; and
  • Keep good records.

The first thing you must do is clearly understand the scope of your new position. Practically speaking, you’ll need to be very careful to follow the rules. For help, the Consumer Financial Protection Bureau (CFPB) offers guides for four types of fiduciaries managing someone else’s money. They can all be downloaded here.

What’s a power of attorney?

A power of attorney for finances is a legal document that gives someone (called the “agent”) the legal authority to make decisions about your money and property. Generally, that legal authority kicks in when the person who granted it is sick or injured. CFPB help for agents under power of attorney can be downloaded here.

What’s a court-appointed guardian?

If a parent or other family member with diminished capacity has not made advance plans via a power of attorney and a judge finds that the person cannot manage their money and property alone, it may be necessary to ask the courts to intervene. Different states have different names for this, but the person appointed to take financial authority is often called a conservator or guardian. CFPB help for court-appointed guardians of property or conservators can be downloaded here.

What is a trustee?

A trust is a fiduciary relationship in which a person gives another person, the trustee, the right to hold title to property or assets for the benefit of a beneficiary (or beneficiaries). The grantor (e.g., your parent or other family member who sets up the trust) transfers money and property into the trust, which lays out the circumstances under which a trustee can step in to manage property and pay bills when the grantor is no longer capable. CFPB help for trustees under revocable living trusts can be downloaded here.

What is a government fiduciary?

A government agency may appoint someone to manage someone’s benefits if that person needs help. That person only manages the recipient’s benefits checks but not other financial affairs. The Social Security Administration calls that person a representative payee. The Department of Veterans Affairs calls that person a VA fiduciary. CFPB help for representative payees and VA fiduciaries can be downloaded here.

Look for signs of financial scams, fraud or abuse

Be on the lookout for sneaky business when you take over the finances of an older parent or family member, especially if it’s sudden or unexpected. Do you or your parent think that there is some money missing? Has your parent tried to send money to someone you don’t know? Are they not able to pay a bill they would normally pay, such as for the mortgage or electricity? Has a caregiver been informally handling their money or bills without full disclosure or legal authority?

Saying “yes” to any of those questions could indicate potential problems. As a fiduciary for your parent, be aware of financial scams and take steps to prevent them. Download the CFPB’s guide to preventing financial exploitation here.

Managing money for a parent or family member can feel like a huge responsibility, but it’s one you don’t have to face alone. Local and state agencies can also help provide resources, referrals, best practices and training. Start with the CFPB guides mentioned here and your employee assistance program to steer you in the right direction.


Do you have a question you’d like answered on the blog? Please email me at [email protected]. You can follow me on the blog by signing up here, and on Twitter @cynthiameyer_FF.


Do You Need a Will?

November 09, 2016

One of the five components of a complete financial plan is estate planning, the foundation of which is a last will & testament. Most people don’t really start thinking about a will until they have kids, but really, everyone should have one, even if it’s simply written on a napkin. Here’s what you need to know:

What is a will? Your will is a legal document that directs what happens to your stuff, names your executor (the person who will be in charge of making sure your stuff gets to whom you direct), and also names your preferred guardian for any minor children you leave behind.

Where can I get a will? First, check to see if your employer offers any type of legal benefit. Even small employers sometimes give you access to an online portal where you can complete a questionnaire and have a basic will created, which is how my husband and I did our first drafts just to get something on paper. Other employers offer the ability to pay a small payroll deduction for access to discount programs. Depending on the cost, it may make sense to join for one benefit year and then have your key estate planning documents drafted to get the full value.

You can also draft and print a will online through a couple of different services like Nolo or Legal Zoom. My first will was done this way and while an attorney reviews your document to ensure it complies with your state’s laws, it’s easy to mess up. I had just moved and put the wrong county of residence on mine, an error I didn’t know I’d made until it was too late to change it. I’m lucky that I don’t know if it would have made a difference, but that’s the big pitfall of the DIY will. A lawyer checks that it complies with legal standards, but would not be able to verify its correctness.

For people who own businesses, have blended families or even just a notable amount of wealth amassed, hiring an estate planning attorney is usually worth the additional cost to make sure the nuances that come along with more complex lives are properly addressed according to your wishes. My husband and I recently signed new wills with an attorney. She not only made sure our plan coordinated with our various savings and distribution wishes, but pointed out provisions we hadn’t thought of such as including money for our future children’s potential guardian to expand her home if needed to accommodate the added family members or allocating money for our future kids to travel to visit other family members like their aunts and uncles. Most lawyers charge a flat fee for this service, ranging from hundreds to thousands of dollars, depending on where you live and what other documents you also need drafted.

What makes a will valid? Each state has laws that dictate the rules. Yes, you can write your wishes on a cocktail napkin, but you have to sign it and many states require you to have two non-named witnesses also sign that you were the person that signed it.

This was actually a bit of a comical complicating factor in the signing of our wills. My husband and I had trouble finding a time when we were both available at the same time as our attorney when we could also have two non-named witnesses present. We finally met our attorney at my local health club where we asked other gym members to witness as we signed! A bit goofy, but it got the job done. A more common place to find witnesses is your local bank.

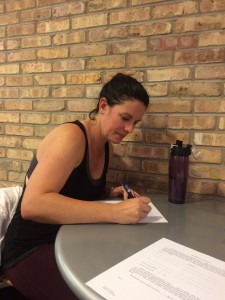
Me actually signing my will

What happens if I don’t have a will when I die? Dying without a will is called dying “intestate,” and your estate is distributed according to your state’s laws. If you’re married, at least part of your estate will go to your spouse in all states. But if you’re not or heaven forbid, you both die at the same time, then the laws vary from state to state. In Illinois where I live, a person who is not married with no children would have their estate split equally between surviving parents and siblings.

I had a college friend whose live-in boyfriend died tragically in his 20’s. His parents weren’t fans of their living arrangement, so she was completely cut out of the funeral arrangements and of course, left high and dry when it came to his stuff. He owned the house they lived in, so she was suddenly homeless too. No one likes to think about dying too young, but a will would have at least made sure she could keep some physical mementos of his.

Can I change it? Yes, and that is an important point to remember. You want to draft your will for how your life is today. Then as life happens, you can always update your will for your new circumstances. Key events that should cause you to make an update would include marriage or divorce, birth or death of a named beneficiary or even a falling out with one of the administrators of your estate like your executor or guardian.

The bottom line is that life can get complicated very quickly, and dying without a will leaves the settlement of your estate to the county probate court where you live. You probably don’t want them making critical decisions for your loved ones. Do your family a favor and put your wishes in writing just to be sure.


The Parents’ Guide to Making a Will

October 31, 2016

Are you raising one of America’s 73.6 million children? If yes, do you have a will? If you don’t have one, you urgently need one. Don’t wait. A will, with a provision which names the person who should be the guardian of your children if you die, is the most important step in making sure your kids are raised by the people you would want to raise them.

What happens if you don’t have a will?

It’s not fun for any of us to think about what would happen if we died unexpectedly. That probably won’t happen, so you might be tempted to put it off thinking it’s silly to prepare for a worst case scenario. The problem is, if you die without a will which names a guardian for your children and specifies what funds are available to care for them, you have zero control over who raises your kids and how much money remains for their support. Your state’s courts, with government social services, is going to decide what happens to your kids, who raises them and how your money is divided up.

You need a will even if your spouse remains to take care of your children. If you die without a valid will, the courts will decide what happens to your assets according to a preset formula (e.g., some to the surviving spouse, some to the kids). Your spouse may not have full access or control over the money allocated to the children.

Don’t feel sheepish about not putting one together yet. According to a Caring.com survey, nearly half of American parents don’t have a will or living trust. Here’s how not to be one of them.

Make three decisions

Once you’ve decided you are going to make a will, it’s relatively straightforward to get started. You’ll need to make three critical decisions before you write anything up:

Name a guardian. Who is the best person to take care of your children until they are adults in the unlikely event that you are no longer living? Does that person share your values? Do they share your beliefs about parenting? Do they love your children?

FYI, in most cases where parents are divorced or unmarried, the default would be for the children to stay with the surviving biological parent, so if you have an objection to that, you’ll need to put that in writing. Choose your first and second choices for a personal guardian to include in your will. You’ll want to name a legal adult who has the time, energy and willingness to raise your children if needed. Before naming a personal guardian, make sure you’ve asked that person and they have agreed to accept the responsibility if needed.

Decide what happens to your money and stuff. Any assets that do not automatically pass according to their title or beneficiary (called “beneficiary of law,” such as property held as joint tenants with right of survivorship,  retirement accounts or life insurance) are included in this category. Make sure you fully designate what happens to your property, bank accounts and investments.

Minor children won’t be able to manage that money for themselves, and you may not want them to have full access to it until they are well established adults. Who will control the checkbook? Decide if that’s an individual – it could be a different person than the guardian if you prefer –  or a trust company.

Name an executor. An executor is a person named in your will (or appointed by the court if you die without a will) whose job is to carry out the instructions in your will. The executor takes care of your last financial business such as paying taxes/bills and re-titling property according to your will. Don’t forget to include a digital executor to control your online and social media accounts, who may or may not be the same as your financial executor. As with a guardian, make sure your executor is someone who is willing and capable to take on that kind of big responsibility.

Prepare your will

Once you’ve made the big three decisions, you’re ready to write your will. Here are some options for preparing a valid one:

Use an attorney. The biggest advantage to using an attorney to prepare a will is that — if you pick a qualified estate planning attorney – you can be more confident that it conforms to the laws of your state. The downside is that it’s more expensive. Check your employee benefits. You may have access to a prepaid legal program as a voluntary benefit or access to lower cost resources through your employee assistance program (EAP). The American Bar Association also offers an online state by state guide to wills and estates.

Use an online legal resource. If you need a basic will without a lot of personalization, an online resource may be a fit for your situation. Check with your EAP to see if you have access to any free or low cost will preparation services. There are also online will preparation sites such as Nolo.com and Legalzoom.com where you can make a will for a reasonable price.

Communicate your plans

Finally, a will won’t help if no one knows you have one. Let a few trusted people, such as a sibling, parent or close friend, know that you’ve prepared a will, and where they can find it if it’s needed. Make sure your executor knows how to access your will and has contact information where needed.

Do you have a question you’d like answered on the blog? Please email me at [email protected]. You can follow me on the blog by signing up here, and on Twitter @cynthiameyer_FF.


The Safety Net of a Group LTC Plan

March 13, 2012

Last week, Prudential, the 2nd largest life insurance company in the U.S., announced they were getting out of the individual long term care insurance market.  Prudential isn’t the first to exit the marketplace since both Guardian Life Insurance and MetLife also recently abandoned sales of LTC insurance.  Although Prudential will no longer be selling any new policies to individuals, they will honor existing contracts and will now be focusing entirely on the group LTC market.  With the marketplace for individual policies shrinking, now may be a good time to add group LTC insurance to your benefits menu. Continue reading “The Safety Net of a Group LTC Plan”

Estate Planning: Governor Brown Has Enough To Do

October 10, 2011

Around the water cooler at the office yesterday, I was congratulating one of my co-workers on her child’s second birthday.  It seems like yesterday when she was pregnant, went into labor a few weeks early at work and we were all running around like chickens with our heads cut off so she almost needed to drive herself to the hospital!  It was something out of a “Three Stooges” comedy.  She made it to the hospital and everything turned out just fine. Continue reading “Estate Planning: Governor Brown Has Enough To Do”