
How Much Will A Hybrid Car Actually Save You?
August 14, 2017When you’re in the market for a new car, how do you figure out which one is going to be the best buy given your situation? Hybrid cars are all the rage in places like California – several of my colleagues drive them. These cars definitely cost more up front than their equivalent gas-powered models, so how do you know if/when you’ll save money?
When my husband Steve and I moved back to the United States in 2010 after living abroad for five years, we had to purchase two new vehicles. We were torn between traditional or hybrid. Because we had put some money aside for the costs of buying new cars when we returned to the U.S., and we also had the proceeds from the sale of our Bermuda car, we decided to buy one of each and track how it worked out over time. (This kind of financial tracking is what happens when an actuary marries a financial planner!)
Here’s what we found.
Our traditional car – loaded and fun to drive
First we bought my car, a Chevrolet HHR, for a little less than $19,000 new from the dealer. It’s an American car, which was important to me, plus it has a back-up camera, satellite radio, sporty details and a manual transmission, which make it fun to drive while improving resale value. Plus, as a small station wagon, it’s been the perfect car in which to fit multiple car seats – and now lots of kids’ sports equipment.
I test drove some other, more expensive cars, but it just didn’t seem worth it at all to spend twice as much money for a luxury vehicle. We have put about 100,000 miles on my HHR in seven years, and get about 26 miles to the gallon (the EPA estimate was 29 on the highway but I mostly drive it around town).
Our hybrid car – very low fuel costs and no frills
My husband Steve originally thought he’d buy a sports car, but ran into the same dilemma. He didn’t find anything he thought would give him twice the driving experience as a less expensive car. Instead, he decided to go with the Honda Insight hybrid, also new from the dealer, for around $23,000. His thought was that he would save on fuel costs during his 23-mile commute to work.
His hybrid is more basic on the inside and has an automatic transmission, so even though it’s highly fuel-efficient, we tend to use the HHR for family road trips. He isn’t as fond of driving his car as the HHR, but he tracks his mileage and he gets 42 miles to the gallon, right on target to the EPA range for that model of 41-43 on the highway. Steve has put about 87,000 miles on his car so far.
Gas prices determine the better buy
Which has been the better buy for us? Maintenance and repairs have been similar for both cars. Both had components which were recalled and replaced at no cost by the dealer.
What it came down to was that it all depends on the price of gas. When we purchased the cars in 2010, gas prices were high, climbing to more than $4 in NJ in 2011. If gas prices had stayed high, the hybrid would be the clear winner in terms of cost. For direct comparison, let’s assume we keep both cars for ten years total with cumulative mileage of 120,000 each. Here’s how it works out:
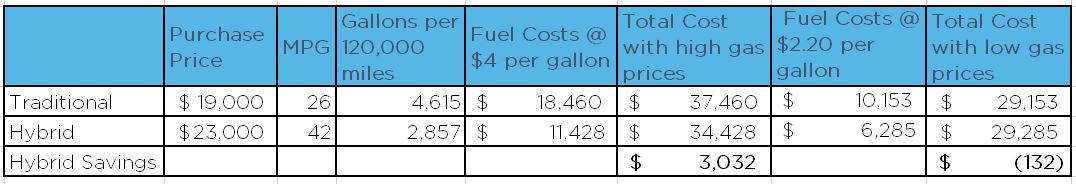
Under the scenario with high gas prices at $4/gallon, the more expense hybrid is the clear winner, saving us $3,032 over ten years.
Gas prices are low now, though, and have been for a few years. What if gas prices averaged $2.20 over the ten-year period? In that scenario the traditional car total costs beat the hybrid by a mere $132.
We’d still buy a hybrid again
There are plenty of other reasons to buy a hybrid car besides savings on fuel costs: going “green,” potentially lower car insurance, and state tax incentives, for example. We are a family who composts, who has solar panels and recycles – so we would be likely to do it again anyway, even if there were not significant net costs savings.
Shopping for a new car
If you’re in the market for a new car, use this method to project future purchase and fuel costs over the time you plan to own the vehicle. Also check out our other posts on Lessons in Car Shopping, Where to Buy a Car, How to Avoid Hidden Car Costs and How to Get the Best Deal on a Car for more useful tips.
Want more helpful financial guidance, delivered every day? Sign up to receive the Financial Finesse Tip of the Day, written by financial planners who work with people like you every day. No sales pitch EVER (being unbiased is the foundation of what we do), just the best our awesome planners have to offer. Click here to join.