
Should You Buy Or Lease A Car? 5 Questions To Ask

November 17, 2017

It might not always seem black and white when it comes to deciding whether to buy or to lease a car. There are pros and cons to each, but there are some things to think about that may have you leaning more in one direction. It also helps to calculate your potential savings to see which makes more sense. When deciding, ask yourself these 5 questions, which should help.

How do you feel about your overall monthly costs?

As long as you lease, you’re renting the car, so you will have a monthly payment. A few things about that:

  • If the thought of always having a payment bothers you because you’re looking for ways to minimize your monthly expenses, you may want to buy a car rather than lease. If you really want to get a big bang for your buck, consider buying one that’s a couple years old with low mileage. Here are some ideas to get the best deal when buying a car.
  • You will have a choice to buy the car at the end of the lease, but the details of the contract matter if you decide to go that route.

Does your current vehicle look like it went through a war zone?

Wear and tear matters with leased cars, so consider the following:

  • If your kids will likely add their own touch, leaving behind stains on your car seats and carpet or you simply find it hard to keep your car in good shape, you may want to purchase instead of leasing. If you return the car in a condition outside of what’s considered “normal” wear and tear in your lease contract, you’ll be responsible for some additional costs. Check the terms of the potential lease for the specifics.
  • If you buy a car, you can pretty much do as you please since you own it. Wear and tear matters more if you want to resell the car at some point later down the road.

How fast do you rack up miles on your car?

There’s typically a limit to the number of miles (usually 12,000 – 15,000 miles per year) you can put on the car during your lease contract. Going over that limit will be an extra cost.

  • If you know you’re likely to go over the approved mileage, but still prefer to lease, consider purchasing additional miles upfront.
  • If you want to drive as far as you want and as often as you want, without restrictions or any additional costs, purchasing might make more sense.

Do you value being able to switch from one new car to the next every 3 or 4 years?

Leasing is an easy way to stay up to date with the newest models available.

  • We all have things that we value and are willing to pay for. If being able to drive the latest and greatest car is something you fancy, the lease could work great for you. Just make sure that constant monthly payments fit within your budget.
  • If you aren’t really into cars or you are the type to keep a car for 10 years, without payments, and feel like you’ve won, purchasing will likely make you feel more at ease.

Do you need a car, but you’re short on cash or don’t want to use your savings?

Depending on where your credit stands, you can typically get into a leased car for either no money down, or very little upfront and you usually have a lower monthly payment.

  • If you want to get into a car without eating up too much of your savings or lack thereof, a lease could work for you.
  • If you don’t want to return the car in the end or be faced with a choice to purchase it or go another route in 3 years at the end of your lease, you may prefer to simply purchase a car upfront.

The decision to buy or lease is a very personal one. It depends on your financial situation and what you prefer and value.

Either way you go, arm yourself with knowledge. If you decide to go with a lease, be prepared to negotiate the terms of your lease. If you decide to purchase a car instead, know what to consider whether you decide to go with a used car or a new car.

Want more helpful financial guidance, delivered every day? Sign up to receive the Financial Finesse Tip of the Day, written by financial planners who work with people like you every day. No sales pitch EVER (being unbiased is the foundation of what we do), just the best our awesome planners have to offer. Click here to join.
How Much Will A Hybrid Car Actually Save You?

August 14, 2017

When you’re in the market for a new car, how do you figure out which one is going to be the best buy given your situation? Hybrid cars are all the rage in places like California – several of my colleagues drive them. These cars definitely cost more up front than their equivalent gas-powered models, so how do you know if/when you’ll save money?

When my husband Steve and I moved back to the United States in 2010 after living abroad for five years, we had to purchase two new vehicles. We were torn between traditional or hybrid. Because we had put some money aside for the costs of buying new cars when we returned to the U.S., and we also had the proceeds from the sale of our Bermuda car, we decided to buy one of each and track how it worked out over time. (This kind of financial tracking is what happens when an actuary marries a financial planner!)

Here’s what we found.

Our traditional car – loaded and fun to drive

First we bought my car, a Chevrolet HHR, for a little less than $19,000 new from the dealer. It’s an American car, which was important to me, plus it has a back-up camera, satellite radio, sporty details and a manual transmission, which make it fun to drive while improving resale value. Plus, as a small station wagon, it’s been the perfect car in which to fit multiple car seats – and now lots of kids’ sports equipment.

I test drove some other, more expensive cars, but it just didn’t seem worth it at all to spend twice as much money for a luxury vehicle. We have put about 100,000 miles on my HHR in seven years, and get about 26 miles to the gallon (the EPA estimate was 29 on the highway but I mostly drive it around town).

Our hybrid car – very low fuel costs and no frills

My husband Steve originally thought he’d buy a sports car, but ran into the same dilemma. He didn’t find anything he thought would give him twice the driving experience as a less expensive car. Instead, he decided to go with the Honda Insight hybrid, also new from the dealer, for around $23,000. His thought was that he would save on fuel costs during his 23-mile commute to work.

His hybrid is more basic on the inside and has an automatic transmission, so even though it’s highly fuel-efficient, we tend to use the HHR for family road trips. He isn’t as fond of driving his car as the HHR, but he tracks his mileage and he gets 42 miles to the gallon, right on target to the EPA range for that model of 41-43 on the highway.  Steve has put about 87,000 miles on his car so far.

Gas prices determine the better buy

Which has been the better buy for us? Maintenance and repairs have been similar for both cars. Both had components which were recalled and replaced at no cost by the dealer.

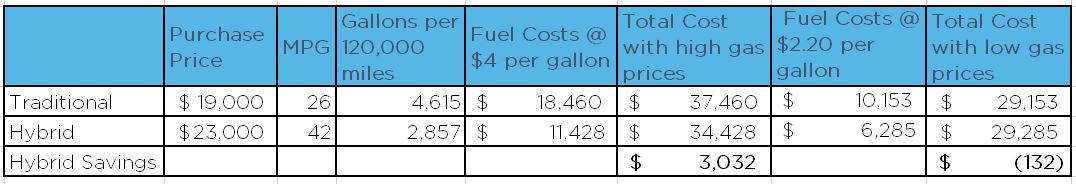
What it came down to was that it all depends on the price of gas. When we purchased the cars in 2010, gas prices were high, climbing to more than $4 in NJ in 2011. If gas prices had stayed high, the hybrid would be the clear winner in terms of cost. For direct comparison, let’s assume we keep both cars for ten years total with cumulative mileage of 120,000 each. Here’s how it works out:

Under the scenario with high gas prices at $4/gallon, the more expense hybrid is the clear winner, saving us $3,032 over ten years.

Gas prices are low now, though, and have been for a few years. What if gas prices averaged $2.20 over the ten-year period? In that scenario the traditional car total costs beat the hybrid by a mere $132.

We’d still buy a hybrid again

There are plenty of other reasons to buy a hybrid car besides savings on fuel costs: going “green,” potentially lower car insurance, and state tax incentives, for example. We are a family who composts, who has solar panels and recycles – so we would be likely to do it again anyway, even if there were not significant net costs savings.

Shopping for a new car

If you’re in the market for a new car, use this method to project future purchase and fuel costs over the time you plan to own the vehicle. Also check out our other posts on Lessons in Car Shopping, Where to Buy a Car, How to Avoid Hidden Car Costs and How to Get the Best Deal on a Car for more useful tips.

Want more helpful financial guidance, delivered every day? Sign up to receive the Financial Finesse Tip of the Day, written by financial planners who work with people like you every day. No sales pitch EVER (being unbiased is the foundation of what we do), just the best our awesome planners have to offer. Click here to join.

3 Reasons You Probably Don’t Save Enough

May 28, 2015

Whether your main financial goal is to pay off debt, buy a home, or retire comfortably, chances are that saving money will be instrumental to achieving it. Yet too many of us just aren’t saving enough. Why is that? The following are the three main culprits I’ve found and what to do about them: Continue reading “3 Reasons You Probably Don’t Save Enough”

Short on Retirement Savings? Here’s How to Save More

August 30, 2013

Have you ever compared your current retirement savings balance to where it should be, according to the advice of a financial adviser or online calculator? Most Americans haven’t. According to the Employee Benefits Research Institute, roughly 60% of Americans have less than $25,000 set aside for retirement and about 30% have less than $1,000. If you haven’t already done so, check on your retirement accounts and see where you stand. If you’re behind and want to catch up, consider the following five strategies. Continue reading “Short on Retirement Savings? Here’s How to Save More”

A Financial Yardstick for Everyone

March 27, 2013

One thing I’ve come to learn after being on the financial helpline for 6.5 years is that some employees simply want to know how they are doing relative to everyone else.  No matter how I try to encourage them to consider themselves and their circumstances unique, human nature drives us to want to know if we are ahead, behind, or in line with our peers.  We crave some type of yardstick to know if we are measuring up.  Continue reading “A Financial Yardstick for Everyone”

Back to School Money Lessons: Making The Most of a Bad Economy

August 27, 2012

My friends are all posting their back-to-school photos of their kids and grandkids – they are so cute with their new clothes and backpacks! I miss the days of dropping my own kids off on those first days of the school year…well, except the first few years. I didn’t let them see a little tear in my eye as they walked into their classrooms looking so grown up.  Continue reading “Back to School Money Lessons: Making The Most of a Bad Economy”

A Tale of Two Choices

May 25, 2012

Over the last few weeks, I have met a couple of young men who are in the early stages of their career.  Both are in their mid-20’s and both make approximately the same amount of money, yet each had very different financial issues to discuss.  The contrast with these two gentlemen is something that I am absolutely going to point out to my kids and hope that they can take a valuable life lesson from it. Continue reading “A Tale of Two Choices”