How I Mooched Off My Parents With My Pride (And Their Retirement) Intact

March 27, 2019

Some of the toughest calls I handle as a financial coach are situations where someone is struggling to make their bills because they loaned money to a loved one or have taken on the responsibility of supporting others. Understandably, they wanted to make things easier for someone they care about, but now they’re under stress because they can’t meet their own obligations.

I’ve been there before

My parents and I experienced this dynamic ourselves almost 20 years ago when I was diagnosed with cancer. I was barely in my thirties and, like most people my age, I was healthy, working hard, and enjoying my free time playing softball, volleyball and boating with friends. 

I was also in the second year of building my own practice as a financial advisor, so my savings account was thin (okay, non-existent). However, my income was steadily growing and I was confident I would be on solid financial ground within 1-2 years.

After my diagnosis, I was not able to work for several weeks during treatment. Since my income was built around commissions, it didn’t take long for the revenue stream to dry up, the savings to be depleted, and the medical bills and credit card balances to start growing out of control. 

The thing that made me cry about having cancer wasn’t having cancer

Strangely enough, I never cried over the diagnosis – I was confident in my medical team and it was beyond my control really. However, I did cry the day my parents wrote a check to cover my mortgage payment. That really broke my heart because I should have known better than to let myself get into that vulnerable financial position. 

Seriously, I talked to people daily about emergency reserves and disability protection and here I was taking money from my parents to pay my bills. I was also fully aware of my parents’ financial picture as government employees trying to retire soon. At that time, we didn’t know how long my illness would go on, but I knew they loved me enough to jeopardize their own futures for me – that’s just the kind of people they are.

Making a plan to pay them back

When I eventually came out the other side with my health intact, we agreed on a payment plan so I could reimburse them for all of the bills they helped me with. My parents insisted it wasn’t necessary to pay them back, but I explained that I had to for my own peace of mind.

So we created a monthly payment plan, put it in writing, and agreed on an interest rate that was minimal. The rate was higher than what they could earn at the bank but much lower than I would have paid to a credit card company (win-win). As my situation improved, I ramped up the payment.

What I learned in the process

It took a few years to fully reimburse them, but I learned several valuable lessons by handling my dilemma this way:

  • Making the most of living below my means: I had developed the habit of living without those monthly payments, so when I was finished, I immediately redirected those dollars to my retirement plan. I had a lot of catching up to do. I had also learned to live below my means, and it felt great.
  • Practicing what I preached: I now practice what I preach and try to maintain 3-6 months of reserves on hand for life’s next unexpected curveball. I also always, always enroll in my employer’s short-term and long-term disability programs.
  • Rethinking career choices: I re-evaluated my career choice and found a full-time, non-sales position with a reliable salary and good benefits (just in case the cancer came back).
  • Respecting my siblings: By paying my parents back for everything, I avoided potential tension down the road with my siblings who may not have appreciated the burden I was putting on our parents or felt I was being rewarded for making poor financial choices (or burning through their potential inheritance).
  • Resolving not to repeat history: I came out of that situation determined not to go through anything like it again.
  • Taking care of the most important thing to me: Most importantly, my parents’ financial future was left intact.

We lost Dad about five years ago, but I’m happy he and Mom passed some great lessons along. They always provided a safe place to fall and never allowed me to hit rock bottom, but they also helped me get back on my feet with my pride intact. 

Protecting Your Identity At Tax Time

February 27, 2019

When it comes to protecting my identity, I’ve had to be super-vigilant since a young age due to my common last name. It was nerve-racking as a teenage college student to be served a subpoena by a sheriff’s deputy and not understand what was happening or why.

A case of mistaken identities

It turned out that a collection agency was trying to collect a sizable, unpaid hospital bill for someone else with an identical name. Thanks to my parents and my unique Social Security number, they were able to squash the matter pretty quickly. Since then I’ve learned there are at least eight other women within 50 miles of me with identical full names — one even shares my same date of birth.

As a result, I’ve learned the importance of protecting my personal information after multiple court summons, mixed up medical records, and attempts at stealing my identity. That’s becoming harder and harder as identity thieves become more sophisticated.

Protecting your tax refund

As we prepare for tax season, there are a number of steps we can take to protect ourselves from identity theft and someone stealing our tax refund.

  • The IRS suggests that anyone who’s been the victim of a data breach should keep in touch with the company that lost your data. Verify exactly what data was stolen and what they are doing to protect you (credit monitoring services, for example). Not all data breaches result in tax-related identity theft.
  • File your income taxes as soon as you you’re able to beat someone else to the punch – a scammer can only steal your refund if they file before you for that year.
  • If your Social Security number was compromised and the return that you e-File is rejected as a duplicate, you should submit IRS Form 14039, an Identity Theft Affidavit. Also use this form if the IRS informs you that you may be a victim. You can fax the form to the IRS at the number provided or mail it along with a paper version of the tax return that got rejected. (yes, the IRS is still that old-fashioned in some ways)
  • Within 30 days of submitting Form 14039, you’ll get a letter from the IRS acknowledging your report. In some cases, you may be asked to prove your identity using their written instructions. It’s important to take those ASAP and follow them closely.
  • The IRS will work with the Identity Theft Victims Assistance team to make sure your latest return is processed and issue a refund, if applicable. They’ll also review past returns to see how many tax years might have been impacted, and they’ll remove any fraudulently filed returns from your record. An identity theft indicator will be placed on your record indefinitely and you may be given a special PIN annually to be included on future tax returns.

Typically, these cases can be resolved in 120-180 days or more than a year, depending on the circumstances. If we have more government shutdowns in the future, it will likely take longer.

Therefore, I’m going to take advantage of this frigid winter to get my tax information organized and get my return e-Filed as soon as possible to reduce the risk of someone sneaking in before me. And yes, e-Filing with the IRS is a safer way to protect your personal information than mailing a paper copy, plus your refund will be processed that much faster!

Important Reminders To Help You Prepare Your Taxes This Year

January 10, 2019

In the coming weeks, Americans will begin preparing their tax returns for 2018 under the tax reform changes that went into effect on January 1, 2018. While many of the changes are intended to simplify tax preparation, the very idea of change can cause anxiety. Here are some reminders to help make your tax season flow smoothly.

Don’t procrastinate

Fortunately, several people I spoke to throughout the past year took advantage of the IRS W-4 calculator and other tax estimators to monitor their withholdings and make adjustments, if needed. Still, there’s nervousness about how the numbers will all shake out.

Ideally, you’re due a refund and you want to get that in your pocket sooner rather than later, right? On the flip side, if you owe, there may be steps you can take to reduce your liability before the tax filing deadline of April 15th or to come up with the cash needed. Either way, just knowing where things stand will reduce your anxiety. Then you can plan your next step.

Understand that there is only one Form 1040 now

To help streamline things, the IRS re-worked the 1040 into a shorter form so that everyone will use the same baseline for their return. The new approach uses a shortened, simplified 1040 that can be supplemented with additional schedules if needed. In addition, they have eliminated the 1040A and 1040EZ forms altogether, so don’t spend valuable time searching for these if you’ve used them in previous years. All of the new forms are available here from the IRS.

Seek assistance if needed

Some of the anxiety associated with tax prep is the fear of making an unintentional error that comes back to bite us. Or maybe it’s just overwhelming or your to-do list just keeps growing. There are a number of options to consider to get that return finished and (fingers crossed) get your refund in your pocket ASAP.

Free filing and resources

The IRS site offers Free File software for households with income below $66,000, including state returns. If your income is greater, you can still download free fillable forms that will do the math for you, but you must know how to prepare your federal taxes. You also don’t get help with your state forms if your income exceeds the threshold, but check your state’s revenue website as they likely offer the fillable forms there.

If you don’t qualify for the IRS resources or want face-to-face help, check your community for pro bono or free tax filing services. For example, the United Way has partnered with tax prep software providers to provide free software to households earning less than $66,000 last year (go to MyFreeTaxes.com to learn more).

For people who generally make $54,000 or less, persons with disabilities, or limited English speaking taxpayers, there’s the Volunteer Income Tax Assistance (VITA) program.

Folks who are age 60 or older can seek guidance through the Tax Counseling for the Elderly (TCE) program, which typically operates through AARP locations, including your local library (search this site for locations in your area).

DIY tax prep

For those who don’t qualify for the free services above or feel comfortable with online apps, there are a number of tools available to reduce anxiety by guiding your through the process and helping to ensure you don’t miss anything. This might be especially helpful in light of the new tax laws.

For those of you who like CreditKarma for monitoring their credit score, they offer free tax prep on their website and recently added free audit defense as part of the service. Reviews indicate they’ve worked out several of the kinks from early years, so it might be worth checking out if your situation is fairly straight forward with W-2 or 1099 income. It’s not a good fit for active traders, real estate investors, or if you have to file in multiple states.

For more complex situations and apps with more bells and whistles, check out this recent comparison of online tax filing services.

Hire a professional

Finally, if your situation is too complex, overwhelming, or you find yourself in an unexpected pickle, you might consider hiring a tax professional. Although the thought of paying for a pro isn’t appealing, they can often pay for themselves by identifying tax-savings opportunities, avoiding minefields, and keeping you informed of the latest tax laws and strategies.

My colleague, Kelley Long, provides some helpful tips on finding a good tax preparer to fit your needs. If you do hire a pro, work with them to help estimate your 2019 taxes and adjust your W-4 for this year if needed as well.


The Ultimate F-word: How I’m Approaching My Goals Differently As Fifty Approaches Me

January 03, 2019

Editor’s note: As we launch 2019, I’ve asked each of our bloggers to reflect on their own personal goals, plans or thoughts on the past or upcoming year. Our hope is that you not only draw inspiration from our sharing over the coming weeks, but also that we are all able to feel more connected through our shared human experience and recognize that no matter where we are on our personal financial wellness journeys, that we all have similar hopes, dreams and struggles. Happy New Year! Here’s what Teresa has to say:

I’ll be reaching the grand age of 50 this June, and I’m determined to reach this milestone with as much grace as possible. On most days, however, it seems my deteriorating body didn’t get the memo.

This year, I had several appointments with my physician, a nutritionist, and other specialists and after being poked, prodded, x-rayed, and scanned, the general diagnosis is simply that “You’re getting older.” What the ****? Can I please have my co-pay refunded?

Since I wasn’t able to find the magic bullet for feeling better, I’ve decided it’s time to get back to the basics for 2019. I’m going to approach my fitness goals using some of the tried and true methods I’ve used when it comes to my finances.

Pay myself first

The phrase “pay yourself first” is popular in personal finance meaning you should save to your investments and retirement accounts first each time you get a paycheck rather than spending it elsewhere and waiting to see what’s left over. By putting your savings on auto-pilot, you’re more likely to reach your goals versus someone who waits until the end of the pay period hoping there are funds left to save.

Using the same philosophy, I’ve learned I have to get to the gym every morning at about 6:00 as a part of my daily routine for any real progress. On the days I’ve planned to get there in the afternoon or evening, some emergency or unexpected fire pops up that needs my attention, and my trip to the gym gets sacrificed. If I get my workout in first thing, I’m energized the rest of day and know that I’ve done something good for myself regardless of how the rest of the day goes.

Moderation works

When it comes to meeting financial goals, we often have to remind ourselves that slow and steady wins the race. For example, I can’t pay off my mortgage early by throwing every extra dollar I have at it until I’ve rebuilt my emergency reserves. If I throw all of my extra dollars at the mortgage, I’ll be in no position to handle life’s next curve ball and will have to resort to a high-interest credit card.

Instead, I make small adjustments with my financial goals like ratcheting up my 401(k) contribution 1-2% every January, making one or two extra principal payments on my mortgage each year, and increasing my “emergency fund” contribution each quarter.

The same approach is true with my daily workouts. I went into my first few workouts this summer with a little too much gusto and spent a week recovering from the damage I did to my lower back. Shivers go up my spine now whenever I see a kettlebell or those battle rope thingy-ma-jigs. I’ve learned that at my age, I have to spend a good deal of time stretching before and after my workouts and I increase my weights slowly each week. I’m getting stronger every week while not doing damage to my muscles and joints.

Stay focused on the goal

When I’m faced with financial decisions – large or small – I’ve learned to ask myself “does this purchase meet one of my goals?” My weakness can be clothes. When I’m tempted to buy a pretty top or something that’s caught my eye, I ask myself, “Does this purchase help me reach any of my goals?” If the answer is NO, then I don’t buy it.

I’m working on asking myself similar questions when I’m just not in the mood to work out…

“Why am I getting up at 5:30 AM?!” So I can get back to rowing and enjoying the outdoors (there are ladies in their 70’s and 80’s doing this!) So I can keep up with my great nephews. So I can remain independent for the rest of my life if God’s willing.

Developing better fitness habits now will help me meet those goals. And studies indicate that I don’t have to kill myself or train like I did as a 20-year-old collegiate rower for results. I can work a variety of programs including strength training, yoga, Pilates, and other fitness routines to stay fit — in moderation.

I just need to find the method that works best for me, make these an automatic part of my daily routine, and stick with it. The results will come — slow and steady — which is just fine at this stage of my life.

How I Stopped The Grinch From Stealing My Christmas

December 21, 2018

A few months ago, I got to travel to one of my favorite cities, San Diego, on business. Having lived in Kansas most of my life, I appreciate any opportunity to see the ocean and enjoy the warm weather, especially when things are getting cooler back home and a cold winter is just around the corner.

Navigating Southern California traffic

Although I’ve visited San Diego before, I’ve never driven in the city and I’m not familiar with the highways and roads. I took a few wrong turns in my rental car, was startled by the motorcycles whizzing between the lines of cars on the highway, and caught a couple of rude hand gestures being directed my way (or maybe there’s a secret “welcome to San Diego” sign I’m unaware of).

Anyway, I trusted my phone’s GPS when she warned for two miles that my exit was coming up on the left. Being the planner I am, I gradually maneuvered my way over to the left side of the highway but avoiding the lane marked for “carpools.” When Ms. GPS finally said “take the exit on the left” … well, I did just that.

The Grinch wearing a badge

At the end of the exit ramp, a member of the California highway patrol leaned down, pointed at me, and promptly waved me over. He explained I had been driving in the carpool lane. I tried to respectfully argue that I had not. He further explained that I had illegally taken an exit for “HO’s only,” which further confused me. Apparently “HO” stands for “high occupancy” and since I didn’t qualify as a “HO,” I was not allowed to use that exit.

Where I come from, HO is what Santa says

I didn’t score any sympathy when I asked why they had to make it so complicated. I explained that I understand “carpool,” but I’ve never heard of “HO,” and I’m from out-of-state in a strange city, and I’m in a rental, etc. Long story short, he was feeling Grinch-y and I received my first ever traffic citation for a whopping $490. To really rub it in, the deadline for payment was just a few days before Christmas.

I fought the law and the law won

My first instinct was to fight it. I used my complementary consultation with an attorney that we have through our Employee Assistance Program (EAP). I also tried to beg for mercy with the court, which was time-consuming from another state. Eventually, I realized the holidays were nearing and I just needed to put on my big girl pants and pay it.

How I kept the Grinch from ruining Christmas

While $490 is enough to be a potential set-back in my financial world, the good news is that I had set two goals back in January, 2018 that would help me through this and ensure my holidays were still festive:

  • First, I had made automatic deposits into my emergency reserves with every check, so I was more than able to pay the ticket without impacting my ability to pay my December bills.
  • Second, and most important for me, I had set up a separate savings account for gifts only and deposited a small, set amount from every paycheck to have enough for Christmas gifts (like my colleague explained in this blog). So, despite the unexpected wallop to my personal finances, I had saved enough to still get gifts for my family and loved ones.

Paying a traffic ticket, especially a ridiculously expensive one that I don’t even feel like I deserved, really rubbed me the wrong way. But I’m not about to let it ruin this time of year for me. I think I’ll just pretend the fat payment I made to the beautiful city of San Diego was a well-deserved gift for the holidays.

Waited Too Long To Start Saving For College? Here’s An Alternate Idea

December 04, 2018

I often speak to parents who feel guilty because they don’t feel they’ve done an adequate job of saving for their child’s education. Like a lot of folks we work with, they graduated with their own student loans, maybe got married, took out a mortgage, had children, paid daycare expenses, had unexpected setbacks, helped their aging parents, and so on, and so on. Saving for education never rose to the top of the priority list.

Time to get serious is often too late

Now that their child is in high school, they know they need to get serious about saving for college expenses, and they’re disappointed when they learn there is no magic investment out there which guarantees a 20% rate-of-return with zero risk to catch up and close the savings gap. One recent caller I spoke to would need to save $1,200 per month to meet the goal. She was so worried about the heavy burden of student loan debt on her child’s shoulders that she was willing to cannibalize her own retirement account to make it happen.

Rather than feeling guilty and jeopardizing your own future, I ask that you consider a mind shift….

An impactful alternative to paying for college

If you can’t offset the tuition and costs of their education today without a major change to your current situation, why not help them get a jump start on their retirement instead, and have your child take out loans for college? Bear with me here: what if instead you could contribute $1M or more to their retirement nest egg at a much lower annual cost than college?

It’s totally possible. Consider the following hypothetical…

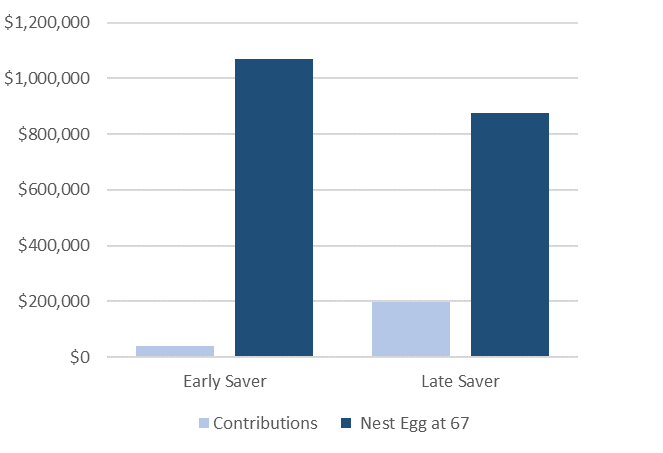
If your 16-year-old teenager works just 15 hours per week at the federal minimum wage, he/she will earn about $5,655 in gross wages in a year. Now what if you and your teenager agree to invest $5,500 in a Roth IRA in their name, the maximum allowed for 2018? Then, make the commitment to invest a total of $5,500 each year (about $459 per month) until your child graduates college as incentive (assuming he/she continues to work and earn at least $5,500 per year).

Assuming graduation at age 22, the total deposits to your child’s Roth IRA after 7 years would be $38,500. Assuming a 7% average return, it would be worth about $47,500 by the time they graduate college. (That might be the equivalent of 2-3 years of college education!)

Now let’s assume no additional deposits or withdrawals. Assuming a 7% average return over the years, the Roth IRA could grow to about $1,026,000 by age 67. Even better, the withdrawals would be tax-free since the funds are in a Roth IRA.

That’s the power of time and compounding. 

Now assume your child waits until age 32 (maybe after all of their student loans are paid off) to start getting serious about their own retirement savings. They start saving $5,500 per year every year until retirement at 67. That makes total deposits of $198,000 for 36 years and, at 7%, it would only grow to about $876,356.

That’s the impact of procrastination.

Starting earlier means saving less and having more

While I’m not suggesting that your child’s retirement should take precedence over education funding, these examples give insight into an alternative way to help your child build a solid financial foundation early on by leveraging the power of time and compounding.

Another benefit to this strategy is that a Roth IRA is not counted as a spendable asset on the FAFSA.

Other ideas if you can’t afford to max out a Roth IRA

If you can’t invest the maximum contribution to a Roth IRA, consider a lesser amount to get them started. Another option is to introduce them to the concept of a “match” by matching any contribution they make with your own contribution dollar-for-dollar. You could even encourage relatives to gift dollars for Roth IRA deposits as well, as long as you don’t exceed the current limit of $5,500 and as long as your child has earned income to match the deposits.

The point is to get them on the track towards a secure financial future without derailing yours in the process.


How To Replace Important Documents

September 18, 2018

Replacing vital documents that may have been destroyed during a hurricane, flood, fire or other disaster can be overwhelming, and since you may not even need some of them for years, it’s easy to forget or not even realize what you’re missing until it’s a critical need and possibly too late. I know that if I lost my home or had it totally flooded, it would take me awhile to even start thinking of what I lost. To that end, I created a list of the items that would be the highest priority to replace, along with links to the various agencies that can help.

Although the process varies with the document type, these general steps can help you get started. Before diving in, keep in mind that many of these agencies may want to mail new documents to you. If the home that you list as address-of-record has been destroyed, you should contact your local post office first and ask if you can pick up your mail or have it forwarded to a new, temporary location prior to having new documents mailed out.

Identification (ID) Cards

State-issued identification

If your driver’s license or state-issued ID needs replaced, contact your state motor vehicle agency. You may need to provide other forms of ID that contain your photo, full name, and date of birth, so confirm with them what you’ll need to bring with you to prove your identity.

Social Security card

Contact the Social Security Administration (SSA) to request a replacement card. This service is free of charge, but there are pretty stringent requirements for proof of ID, so you may need to complete some of the other steps first. You can also call (800) 772-1213 or visit a local Social Security office.

Medicare ID card

The SSA can also help you replace a lost or destroyed Medicare card.

Medicaid ID card

Contact your state Medicaid office to request a replacement.

Permanent Resident (green) card

The U.S. Citizenship and Immigration Services (USCIS) can help you replace a lost or destroyed permanent resident (green) card.

Military ID card

Learn how to report a lost or destroyed military ID card and how to get a replacement. You’ll likely have to go to a local office to apply.

Passport

If your passport was lost, destroyed, or suffered water damage, you must report the loss immediately. Once you report it, it is invalidated by the State Department and can’t be used if it is found later. However, taking this step may be one of the first you need to take in order to provide proof of ID for some of the other documents you’ll need.

Replacing a damaged passport

Passports that have water damage can no longer be used. In order to replace it, you’ll need to apply in person at an acceptance facility or at a local passport agency. You will need the following:

  1. The damaged U.S. passport
  2. A signed statement explaining the damage
  3. Form DS-11 (Application for U.S. passport)
  4. Citizenship evidence (i.e., birth or naturalization certificate)
  5. A photocopy of citizenship evidence
  6. Present ID (in person)
  7. A photocopy of ID
  8. One passport photo
  9. The ability to pay the fees

Replacing a lost passport

If your passport is completely gone, you will also need to apply in person and include the following:

  1. Form DS-64 (Statement regarding lost or stolen passport)
  2. Form DS-11 (Application for U.S. passport)
  3. Citizenship evidence (i.e., birth or naturalization certificate)
  4. A photocopy of citizenship evidence
  5. Present ID (in person)
  6. A photocopy of ID
  7. One passport photo
  8. The ability to pay the fees

According to my research, if your citizenship evidence was lost or damaged as well and you are unable to replace them before applying for your passport, you can request a file search for an additional fee if you have previously been issued a passport.

Expedited service

If you are traveling in two weeks or less or need a foreign visa in 4 weeks or less, you can make an appointment at a passport agency for expedited service. This is the quickest way to get your passport, but you will be charged an additional $60. You can make an appointment online or call (877) 487-2778.

Vital records

Birth certificate

If you were born in the U.S.

Find the vital records office in the state where you were born and check with them to see if you can obtain a certified copy of your birth certificate without any identification and follow the instructions.

  • A few states don’t require a government-issued photo ID, or they will accept other solutions like a sworn statement of your identity. Some states allow your mother or father whose name is on the birth certificate to submit a notarized letter with a copy of their own photo ID.
  • If you need to get a copy of your birth certificate quickly, ask the vital records office at the time you place your order about getting expedited service or shipping.

If you were board abroad or on a military base outside the U.S.

If you were born to American parents abroad, they should have registered your birth with the U.S. Embassy or consulate in that country and received a Consular Report of Birth Abroad. You can get a copy of this report from the U.S. Department of State. Depending on the country, a vital records office in the nation may also list the birth.

If your parents did not register your birth with the U.S. Embassy, you may have to contact the hospital where you were born. You may also try contacting the base operator or public affairs office for the appropriate military branch if you were born on a base.

If you were born abroad and adopted by a U.S. citizen

The country in which you were born issued your birth certificate, so that adds another wrinkle. If you need a replacement, contact the nearest foreign embassy or consulate for that country to get started. A child born in a foreign country and adopted by a U.S. citizen does not receive a U.S. birth certificate. If the document is in a language other than English, you should also seek the embassy’s help in getting the document translated if you require authenticated documents.

If you have a child who was adopted from a foreign country and you need their birth certificate, fill out an application for replacement of naturalization/citizenship form or contact U.S. Citizenship and Immigration Services for further help.

Marriage certificate

To obtain the document that proves you were married, contact the vital records office in the state or county where you got married. Even though the guidelines vary by state, all requests will require:

  • Full names of both spouses at time of marriage
  • Month, day, and year of the marriage
  • Place of marriage (city or town, county, and state)
  • Purpose for which copy of marriage certificate is needed
  • Relationship to persons whose marriage certificate is being requested
  • Daytime telephone number (include area code)

Death certificate

You may need to provide a copy of the death certificate of a spouse or other family member for a variety of legal reasons including life insurance claims, pension benefits for a surviving spouse, or spousal Social Security benefits; applying for Medicaid benefits; changing joint bank and credit card accounts, utilities, mortgages, vehicle titles, and leases; and remarrying.

If the death occurred in the U.S.

You can request a certified copy of a death certificate from the vital records office of the state or territory in which the death occurred. See the instructions for that state or territory for details such as fees, address to write to, and the requestor’s required identification. In addition to your state’s requirements, all requests should contain:

  • Full name of the person whose death certificate is being requested
  • Their sex
  • Their parents’ names, including maiden name of their mother
  • Month, day, and year of their death
  • Place of death (city or town, county, and state; and name of hospital, if known/applicable)
  • Purpose for which the copy is needed
  • Your relationship to the person whose record is being requested
  • Your daytime telephone number with area code

If the death occurred outside the U.S.

You will need to obtain a copy of the Consular Report of Death of a U.S. Citizen Abroad for U.S. legal proceedings. See Death of an American Abroad for details on obtaining a copy of this report.

Divorce decrees and certificates

A divorce decree is an official document from the court that grants the termination of a marriage. It includes specific details of the divorce and is issued by a state vital records office. A divorce certificate shows that a divorce occurred but does not state all of the same information as a divorce decree. Either may be required in a variety of instances later in life, so you’ll want to make sure you have a copy.

U.S. divorces

Divorce Decree: contact the “county clerk’s office” or “clerk of the court” for the county or city in which the divorce was granted.

Divorce Certificate: Contact the state vital records office in which the divorce was granted.

Overseas divorces

If the divorce occurred outside the U.S. and you are in the U.S., contact the appropriate country’s embassy or nearest consulate to find out how to get a copy of the divorce decree.

United States law does not require U.S. citizens to register a foreign divorce decree at an embassy. But if the foreign country in which your divorce took place is a signatory to the Hague Convention on the Authentication of Documents, you may bring your divorce decree to a U.S. Embassy or consulate to have it certified.

Military records

Request Standard Form 180 (SF-180) from any office of the Veterans Administration, American Legion, VFW or Red Cross, or download from government archives.

Other documents

  • Voter registration card – your state or local election office
  • Naturalization or citizenship documents – Contact Citizenship and Immigration Services
  • Mortgage papers – Contact your lending institution
  • Property deeds – Contact the recorder’s office in the county where the property is located
  • Insurance policies – Contact the insurance company for replacement policies
  • Savings Bonds – Complete Form PDF 1048 (Claim for Lost, Stolen or Destroyed U.S. Savings Bonds); available by calling 304-480-6112 or at www.treasurydirect.gov/forms/sav1048.pdf

Credit cards

  • American Express: 800-528-4800
  • Discover: 800-347-2683
  • MasterCard: 800-622-7747
  • Visa: 800-847-2911

Food stamps or EBT card

Food stamps are provided by the Supplemental Nutrition Assistance Program (SNAP). To report a lost card or re-establish benefits, contact your state’s program here.

Your will, powers of attorney, trust and other important legal documents

If you used an attorney, chances are they kept a copy for you. If you’ve made a contract or agreement with someone, chances are they have a copy as well. If neither is the case, then you may need to have new documents created.

Other helpful links

USA.gov – Replace Your Vital Records

National Center for Health Statistics – for links to other states’ vital records.

Take it one thing at a time

Some of these documents will be crucial to continuing daily life, so you’ll want to prioritize replacing them as soon as you can. Others can wait, but if you’ve lost any of these during a recent disaster, try to make time to slowly work on the process of obtaining replacements so you’ll have them when you need them.