Beware Black Friday ‘Deals’

November 23, 2018

As we see the full retail advertising onslaught and stores open ridiculously early for Black Friday (some are even opening on Thanksgiving Day now, which I find appalling), please try to remember a couple of things:

1) This is the time of year when emotions can override logic and overspending can occur. I have spoken with countless people who end up with a sizeable chunk of credit card debt because of holiday spending. Go into the shopping season with a list (wow, I’m becoming my mother!) of who you are buying gifts for and set a budgetary target. Then, stick to those targets. Those Black Friday “deals” may not seem like such a deal if they have 19.9% interest tacked on to the balance next summer.

2) The people in your life, if they are anything like me, will be happier to spend time with you than they are with any gift that you might buy. I’d wager that if you think back over the last several years, you probably can’t remember what you bought for each person on your list or what they bought for you. It’s a season of friends, family and togetherness – not retail profits.

Drink some cocoa, enjoy your friends and family – and have a safe, fun, and financially secure holiday season.

How To Figure Out What You Can Safely Withdraw In Retirement

September 14, 2018

In conversations with people who are very close to retiring (within the next 3-6 months), the financial planning rule of thumb of a 4% “safe withdrawal rate” often comes up in our discussion. It seems as though it’s become an almost universally accepted “rule” and is rarely questioned. To combat complacency and willing acceptance, I routinely question it, making it the starting point for conversations regarding retirement income.

How the “4% rule” works

First, let’s do a quick review of the 4% rule, which is a guideline that people like to use to determine how much they can safely withdraw from retirement savings without risking that they’ll run out in the future.

The rule says that if you have $500,000 in your investment portfolio (401k, IRA, taxable accounts – all combined), you can withdraw 4% of that – $20,000 in Year 1 of retirement. In Year 2, if inflation is 3%, you would withdraw $20,600 (your 4% starting withdrawal PLUS a 3% inflation adjustment).

You continue increasing your withdrawals annually until you are leaving the balance as an inheritance to your heirs and/or charitable organizations. It’s worth noting that the person who “invented” the 4% rule (Bill Bengen) retired a few year years ago and his retirement strategy is very close to using the 4% rule.

Doing a reality check

When talking with almost-retirees, I like to give them a look at the first year under this scenario. If pension income will be $900/month, Social Security will be $2,100 and investment withdrawals add up to $1,667 from the 4% example, I like to do a “back of the napkin” reality check with them. Can they really get by on $4,667 before taxes each month?

We look at their after-tax income as a result of that question and also review their current budget categories and expected level of spending. Some expenses will inevitably decrease (dry cleaning or gasoline, maybe housing) and some will inevitably increase (like health care). Of course, this is merely a starting point for conversation, providing a situation to discuss the limitations of the 4% rule and provide other ways to figure out a “safe withdrawal.”

Reviewing the flaws of the “4% rule”

An article with an economist discussing the limitations of the 4% rule points out a few of the flaws inherent in using that rule for all retirees:

  • Retirement isn’t a “one size fits all” proposition. Everyone has a different scenario and different goals. Is your goal to spend every last dollar before you die or is it to leave a significant legacy? The answer to that question, amongst others, will help you determine if the 4% rule might be an appropriate starting point.
    • My take: Don’t retire and start a distribution stream without having serious conversations about your most important life goals with a financial professional and developing a strategy for distribution of your assets.
  • Sequence of returns is critical in the simple 4% strategy. What happened to someone who retired in 2008 & had a 4% withdrawal on top of a 40% market loss? Chances are they ran out of money much sooner than planned. The early years of retirement are exceedingly important for someone considering a flat withdrawal rate.
    • My take: You can minimize the impact of a potential market drop through asset allocation and by having a surplus of cash on hand. I talk with soon-to-be-retirees about the concept of having 3 YEARS worth of expenses in cash or very short-term fixed income to start retirement. Most market downturns won’t last more than 3 years and using that liquid surplus to live on during down markets can allow you to ride out the storm from a position of relative safety.

Looking at different models

In the New York Times article, Wade Pfau (the economist mentioned earlier) looks at a few different models (constant spending, floor & ceiling rules, and a complicated set of “decision rules”) that various financial professionals have developed to deal with weaknesses and limitations in the 4% rule. The part of the article that I find most interesting is that in every model, people almost always UNDERSPEND in retirement, leaving a significant inheritance (which my kids better not be expecting to happen in my life!!!).

While most of the models show a significant sum left at life expectancy, there are scenarios in each model where the portfolio is depleted. There are no “sure things” when it comes to projecting future returns and future expenses and no one knows (or probably should know) the exact date of their own death.

How I plan to make withdrawals in retirement

Here’s the conservative approach that I plan to use when I retire. I’ll start with the 4% rule in mind, but I’ll have a safety net of 3 years worth of cash sitting in a money market account. In years where the market has gone up, I’ll withdraw 4% or more if I want to travel or have large expenses, up to the amount of investment gain that year.

In down markets, I’ll use the cash on hand & suspend any withdrawals from the portfolio. That can virtually eliminate the sequence of returns/early years risk and build in some margin for error. It won’t assure that I don’t run out of money, but it does provide some upward latitude in good years and some protection in down years.

Everyone’s approach will be different

While that’s my planned approach, at least as of today, it may not be right for you. Have you had conversations with your advisors and/or your spouse about your approach? Are you more concerned with running out of money later in life, or not having enough money to spend early in retirement when you’re at your most active?

Retirement clearly is not a one-size fits all approach and I strongly suggest looking at several scenarios based on your assets, income streams and current spending levels. Once you retire, it’s usually permanent. Taking the time to work through your specific situation BEFORE you retire can save you mountains of financial stress during retirement.


A version of this post was originally published on Forbes.

Why You Might Want To Think Twice About 529 College Savings

May 29, 2018

As a financial planner, I meet with people far too often who have a child who is just entering their sophomore year of high school and they have yet to start planning for college expenses. I don’t often recommend waiting until there are only two years before the funds are needed to pay for what may be a gigantic expense — the best recommendation I have for people who want to save for college is to start as early as possible.

However, I’m not sure that the most popular way to save for college, which is the Section 529 College Savings Plan, is the best way. Everything I read and what we often teach as planners is to start a 529 plan as soon as a child is born, make ongoing contributions and have family members add to them at birthdays and holidays. In spite of that, I’m personally not a huge fan of the 529 and don’t think the conventional wisdom surrounding 529’s is all that wise.

What I don’t like about 529 plans

Lack of flexibility

If your kid decides not to seek higher education after high school, getting the money that is inside the plan out for other uses has a cost. All of the growth of the funds becomes taxable along with a 10 percent penalty. If, alternatively, the assets were held in a brokerage account, capital gains would usually be taxed at a lower rate. Converting capital gains into ordinary income for the purposes of taxation is usually a horrible idea, and it’s even worse when a penalty is attached.

One of my favorite ways to see college funded is with the use of low cost index funds in the name of a parent. The upside is that it is truly an asset of the parent and is treated as such in the FAFSA formula. And, if the child opts for a path other than college, BONUS! You have an extra pot of money to fund retirement, pay down debt or check a few items off the bucket list.

Fees

Fees in many 529 plans are higher than you might be able to find with a low cost index fund. While we’ve all heard “past performance is not an indication of future results” a million times, we hear less about what has a higher correlation with future performance: low fees. If a 529 plan is a part of your college funding plan, do a quick fee analysis to make sure that you are not paying multiple layers of fees that drag down your performance.  The savingforcollege.com website has information on any 529 I’ve ever tried to review and is a great resource to help evaluate your alternatives.

Other ways to plan, save and pay for college

Choosing a lower cost school

Without question, the single biggest factor to consider regarding the funding of your child’s education is school selection. I’ve talked to too many parents who don’t want to tell their children “no” when it comes to their dream school, even if it creates a financial nightmare for the family. I’ve also talked to a lot of recent grads, suffering under the weight of crushing student loan debt, who wish that someone in their life had questioned why their “dream school” made sense.

There is some merit to kids doing two years at a community college or a low priced university before transferring to their #1 choice of school for the final two years. School choice is by far the best way to manage education costs, so make sure you are having those difficult but needed conversations with children about the economics of college. Does it make sense to pay $250k for a degree that results in a $35,000 starting salary?

Home equity line of credit

Another way I’ve seen people fund college costs is with a home equity line of credit. It usually beats the interest rate on Parent Plus loans and private student loan interest rates. It provides a lot of flexibility, given that you can pull money from it any time and pay interest only while the loan is in force.

After the last graduation, when flexibility isn’t needed, it can be converted to a fixed rate, fixed term loan or the payments can get accelerated. And while the interest is no longer tax deductible for this type of credit, it still might make sense. For homeowners with significant equity, this is a fabulous option and those who have smaller children can put themselves in position to use this pool of funds later in life by paying additional principal with each mortgage payment and trying to drive the principal balance as close to $0 as possible prior to needing to write a tuition check. Just remember that your home is on the line if you can’t make the payments though.

With as many options as there are for ways to fund college expenses, if your game plan involves a 529 plan perhaps it’s time to re-think your assumptions and strategy. What pools of money could you use instead of a 529? How can you reduce the overall need for funds? What happens if a child opts to not pursue college? There are a lot of variables in this equation and talking with a financial professional who has your interests first and a product sale last on the priority list could be a way to build the right plan for you and your children.

What I Wish I’d Known Before My Divorce

April 03, 2018

As a guy who has gone through a divorce, I always feel a special need to help those who are about to go through that process or who have gone through it and are in the process of rebuilding. I joke that prior to my divorce, I was on track to retire by 55 and live very comfortably, and after the divorce, I’m on track to retire at 85.  But…I’ve never been happier!

What’s it worth?

Is a smile on your face and a lighter mental burden worth an extra 20-30 years of working? For me, the answer is a clear YES, but so many others wrestle with that question for years before either remaining in the marriage or going through a divorce.

I’ve talked with a number of people recently who are not sure which direction their marriage is going. They wanted some ideas on how to be prepared financially so that they are not devastated or blindsided by things that could happen if the marriage ended in divorce. I always hope that they can work on fixing whatever is wrong in the marriage, but if they go down that path, here are a few things that I wish I had determined in advance:

1. Property values

In my divorce, there was an enormous amount of time spent on arguing about the value of my boat. I lived on it for the first 3-4 years after we ended the marriage and I thought it was worth far less than my ex thought it was worth. Boats are a non-essential item and after the housing collapse, stock market collapse and abysmal economic recovery, boat values dropped substantially. I knew people who bought boats in the mid-six figures and couldn’t give them away during the recession. (Between maintenance, slip fees, gas and insurance, boats are not low-cost items.)

Each spouse should complete (separately, without comparing notes) a financial statement from a court or this net worth & budget worksheet. This will be an important part of any financial settlement and could help identify areas where spouses view things differently. If one spouse has an asset that is valued at $10 and the other has it valued at $100,000, there is an obvious discrepancy here.

Getting it resolved out of court

A resolution to that situation prior to a court ordering an independent valuation can be a major cost saving and can also prevent months and months of delays.  (Delays are costly….trust me on that one!) Similarly, if one spouse has an asset (such as an interest in a family-owned beach house) on their sheet and the other spouse does not, filling out this form can help reconcile the differences prior to mediation or litigation.

2. What is going to happen with the primary residence?

Again, this was an area of contention in my divorce. The smart thing to do financially would have been to sell the house and for each of us to buy smaller places in the same school district. My ex, however, grew up in the neighborhood where the house is located and she was committed to staying there.

My initial thought was that she wouldn’t be able to make that work financially (What do I know? I’m just a financial planner) even with alimony and child support thrown in. She was given 3 years to refinance to get my name off of the mortgage.

When it goes wrong

However, in those 3 years she apparently had some other financial things happen that caused her credit score to drop and she couldn’t get approved for a refinance on her own. So I was stuck on the mortgage, and when she missed mortgage payments, my credit score took a big hit.

That created a problem for me recently when I was applying for a mortgage on my current house. In retrospect, I should have fought harder to make the refinance happen instantly or else sell the house. I was more concerned with not disrupting my kids’ lives than with my credit score and it has caused some longer term irritation.

The house is usually the #1 financial obligation in most marriages, and having a well thought out game plan for what to do with it will save you from headaches down the road. Know what your current costs are and what your future costs will be if you move out of the existing house and either buy another home or rent a place. Americans spend a large percentage of their income on housing, so using a divorce as a way to downsize your housing costs can prove to be a spectacular long-term decision.

3. To litigate or mediate

My ex and I did a full-blown litigation since only one of us wanted to mediate or collaborate. We are all entitled to our opinions and our own decisions, but at times those decisions can be rather costly! If at all possible, working with a mediator or collaborative divorce attorney can be far easier and less expensive than a full-blown litigation. Having a conversation with your spouse (or soon-to-be-ex spouse) about this in a calm setting where you can make clear headed decisions can be a tremendous cost saver.

If you are looking for a mediator, here are some things to consider. And for those who haven’t heard of collaborative divorce, here’s a quick primer on it. Either mediation or collaborative divorce can lead to a far friendlier, more positive and less expensive outcome than traditional divorces that go to litigation.

4. Future expenses

This one sounds simple and maybe basic, but far too many people don’t know what the “day after the divorce” looks like. In working with someone who is just starting the mediation process, we determined that she would not be able to afford her home. She is now considering selling the house and using the equity to buy a small condo that could be paid off in 10 years after the divorce.

She’ll actually be closer to her retirement goals as a single woman than when she was part of a two-income marriage! Using the net worth and budget worksheet to project what life looks like post-divorce will help guide some decisions about where to live, what expenses might need to be minimized, and if there are things that need to just flat out be eliminated. It’s tough to picture this, but it’s worth the effort.

Divorce is costly as it is. Not preparing in advance can only make it more so. If you are in the process of contemplating a divorce or are in the early stages, taking these steps could help you walk through the process with as little damage to your long-term goals as possible.

How One Couple Got (& Stayed) On The Same Page About Money

January 12, 2018

The new year is a perfect time to take a look back at the progress you made in your financial life last year and kick it up a notch for this year. So many New Year’s resolutions fall by the wayside by St. Patrick’s Day (eating less ice cream and calling old friends always makes my list – and by April there’s ice cream in the freezer & old buddies still get the occasional “like” on Facebook but not the catch-up phone call). There are some resolutions though, that are not only good for you but sustainable. And maybe a bit more realistic than my ice cream resolution too. Here’s one of those examples.

When the splurges add up

I recall talking with an acquaintance this time last year and she was having some financial difficulty. She and her husband had just bought a new car because their old one had over 250,000 miles on it. They paid about $4,000 more than they had budgeted after they fell in love with one particular car.

They had also renovated a bathroom, and the costs ran higher than expected. Finally, they went “a little overboard” (her words) on Christmas shopping (using credit cards). In isolation, none of these issues would have been an issue. The combination of all 3 things made them feel very constrained — almost overwhelmed — once the dust settled and they looked at the monthly expenses after their winter spending spree.

A difference in principles

She made a New Year’s Resolution to get her spending under control and, for the first time in her life, to understand where her money went — she wanted to see her financial “big picture.” Until that point, her guiding principle had always been, “I have a good job and make enough money to spend what I want to spend and I’m not extravagant, so it’s not a problem.” Her husband was more fiscally conservative and this difference was starting to put stress on their marriage.

Figuring out the big picture

After some conversation with both of them, we sat down together with the goal of organizing their financial life. We used this financial organizer in order to help them see the big picture – what they own vs. what they owe.

They had never put everything on one page before, so this was enlightening for them and probably not in a good way. They thought they were much further ahead than they actually were. We also used a combination of this expense tracker and Mint.com to help them get a firm understanding of where their money was going each month.

Setting a team goal

Upon having this “aha moment,” they made a promise to each other, and a New Year’s resolution, to work as a team this year. Their goals were to:

  • reduce their debt
  • maintain spending discipline
  • update their financial worksheets on the 1st weekend of each month

Teamwork makes the dream work

I saw them in the grocery store recently and asked how their resolution from last year is going. They smiled! Putting it on paper and choosing a sustainable “resolution” made it so they could stick to the plan and even create some healthy new money habits. Now they hold their monthly “financial meeting” at a local breakfast hot-spot, and it’s become a no-kids breakfast date that they look forward to. I have never seen them look happier.

Want more helpful financial guidance, delivered every day? Sign up to receive the Financial Finesse Tip of the Day, written by financial planners who work with people like you every day. No sales pitch EVER (being unbiased is the foundation of what we do), just the best our awesome planners have to offer. Click here to join.

2017 By The Numbers

January 01, 2018

Happy New Year!

As we launch into 2018 here at Financial Finesse, we are reflecting on a successful 2017 — a year of tremendous growth in our business as well as in the number of lives we’ve had the privilege and honor to change for the better. We hope that this blog, written by our own financial planner team, has helped you to have a more prosperous year. Here’s a breakdown of what our readers loved this year, by the numbers:

Total pageviews for the year:

157,121

Most popular posts from 2017:

  1. What Are Your Health Insurance Options When Retiring Early? – 1,378 views
  2. How To Have The Money Talk – 1,250 views
  3. How To Avoid Borrowing From Your Retirement – 1,037 views
  4. Do You Need A Cohabitation Agreement? – 805 views

Most popular posts from previous years:

  1. Is Paying Off Your Mortgage Worth Losing The Tax Deduction? – 8,106 views
  2. What An Accident Taught Me About Car Rental Insurance – 5,939 views
  3. How To Be Financially Independent In 5 Years No Matter What Age – 5,275 views

Most shared on Facebook:

  1. Even Jay-Z Has Investing Regrets
  2. The Trouble With More
  3. How My Money Attitude Was Keeping Me Poor
  4. 3 Important Adulting Lessons I Taught My Daughters

Most shared on LinkedIn:

  1. Should You Go Into Debt To Get Pregnant?
  2. The 5 Things You Should Do Right Now To Protect Your Identity
  3. Why You Shouldn’t Worry About Investing At The Top
  4. How Much Will A Hybrid Car Actually Save You?

Readership by city:

New York: 5,638 readers

Chicago: 4,032 readers

Los Angeles: 3,995 readers

Hartford, CT: 2,248 readers

Golden Valley, MN: 1,686 readers

Lives changed:

Countless

Thank you for being a part of our amazing year! Here’s wishing us all a happy, healthy and financially well 2018!

How Technology Has Helped Me Keep Closer Tabs On My Goals

December 29, 2017

Note from the editor: As we round out 2017, many people will be setting goals and intentions for the year ahead. To help with that, our blog team will be sharing their take on goals throughout the week — we all have a different opinion! We hope you enjoy hearing how each of us approaches the idea of goal-setting and New Year’s resolutions. From Michael:

You’ve probably heard the old expression about the cobbler’s children not having shoes. As a financial planner, I have to admit that looking at my own finances is sometimes a chore. After talking with people about financial issues all day long, the last thing I want to do at night is look at my own situation. I’d much rather turn on some music or podcast or a news channel or even clean a bathroom or read a good book. If keeping better tabs on your daily money is on your list of goals, perhaps my experience can help.

Tracking the day-to-day

What I have found lately is that it isn’t always a chore to keep an eye on my budget, which is great. Technology has allowed me to get a quick look at my financial life at a glance and it’s not all that intrusive. I use an online budgeting tool (there are lots of them to choose from now) to keep track of my spending, and to set monthly targets. When I reach or go over budget in a category, I get an email or a text message. This tool also has an app, so I can take a quick peek at my daily financial life as I’m waiting for coffee to brew (or popcorn to be ready in the microwave).

There’s an app for that

A recurring bill is due? I get a text message to let me know that the statement has been generated and a link to the website so I can schedule a payment. Need to check out if the stock market has gone up or down? A quick look at one of the apps on my phone can give me specific stock quotes, a look at the overall markets, big news items. Wondering what’s going on in the financial world? There’s an app for that too.

Information overload

Whether it’s the world at large or my own personal day-to-day financial management, it’s getting easier to keep track of your financial life without a big investment of time and effort. Is there a downside to this? Absolutely: information overload. At one point I got so many notifications on my phone each day that I stopped paying attention to them & eventually turned them off. I had to unsubscribe from all but a few of the most useful email lists. These apps only work if you work them into your daily routine.

The missing app 

Here’s where my 2018 goal comes into play: I have only been able to find useful ways to manage my day to day; my long term financial picture is something I still visit only periodically. I know my long term goals, and use technology to manage the short term items in a way that is consistent with my long term goals, but I wish there was a way for me to check my progress at a glance for the big picture stuff without having to crunch all the numbers and look at several different accounts first.

If I can find a technologically simple way to view my long term financial goals, then I will consider my 2018 money goals a success — after all, I’m doing all the day to day stuff, so they should, in theory, lead to achievement of the long term. But having a way to check that regularly would help to ensure that outcome.

When used in the appropriate amount, technology can add a great deal of structure and clarity to your financial life and goal setting.

Want more helpful financial guidance, delivered every day? Sign up to receive the Financial Finesse Tip of the Day, written by financial planners who work with people like you every day. No sales pitch EVER (being unbiased is the foundation of what we do), just the best our awesome planners have to offer. Click here to join.

Would You Consider This One Thing To Be A ‘Conservative Investment?’

December 22, 2017

As someone who has a moderately aggressive investment approach, I recently had a conversation with a friend who has a very aggressive investment approach (in my opinion) that made me rethink a piece of my investment philosophy.

Safe lifestyle, ‘risky’ investing style

Here’s his story: he & his wife, who are both 50, have put four kids through college (all four graduated with absolutely no student loans), will completely pay off their mortgage by age 55, and have amassed roughly $500,000 in the combination of their 401(k) plans & IRAs. They have no significant savings outside of retirement plans, but given the amount of spending they have done on the kids’ education, that is hardly a thing to worry about today.

They are hard workers and excellent savers. Their lifestyle entails very little in the way of risky behavior — they eat nutritiously, exercise regularly, do good deeds in the community, and live a fairly frugal lifestyle. We had never talked about money before, so I was surprised at what I learned — I guess I just assumed he’d be relatively averse to market risk with his investments as well.

All-in with stocks

When we started talking about how our retirement accounts are invested, he told me that he is invested 100% in the stock market and has no plans to “get more boring & conservative” over time. When I expressed surprise at his attitude toward completely excluding bonds and cash, even as he approaches retirement age, he said something that changed my perspective. In his opinion, Social Security fulfills the “conservative” bucket in his overall investment life.

Doing the math

According to his math, since he plans to work another 12 years (to get to age 62), between contributions to his retirement accounts and the growth of that money, he is expecting to have about $1 million saved at that point. If they retire at 62, he and his wife will receive roughly $2,800 per month in Social Security income ($1,500 for him, $1,300 for her).

Social security as an income-producing asset

Here’s the twist: since he considers Social Security income his “bond & cash” portion of his investment portfolio, he calculated its equivalent in income-producing bonds. He assumes that if you buy long term US Treasury Bonds, you should average a 4% – 5% rate of return over a long period of time. How much would you need in Treasuries to earn $2,800/month?

Using his return estimate, he would need to have between $672,000 and $840,000 invested in bonds producing 4 – 5% in order to generate a solid $2,800/month indefinitely. So, when looking at his $500,000 retirement accounts, he thinks he has way less than 100% invested in stocks. In his viewpoint, his current mix is 37% stocks, 63% bonds because of the $840,000 that would be required to generate that Social Security income (he used the biggest number available to exaggerate his point!).

Competing viewpoints

I thought he was an aggressive investor because of the way his accounts are invested and he thinks his portfolio is far too conservative. While I think he has a point, I don’t think it’s an appropriate way for most of America to start viewing their investment accounts — Social Security isn’t a given for most people under the age of 45, and he doesn’t factor in the fact that he can’t tap his SS payment early if he needs a lump sum for something like a new roof or hip replacement. But it is an interesting way to look at any type of guaranteed monthly income, since that is a relatively safe “investment.”

Want more helpful financial guidance, delivered every day? Sign up to receive the Financial Finesse Tip of the Day, written by financial planners who work with people like you every day. No sales pitch EVER (being unbiased is the foundation of what we do), just the best our awesome planners have to offer. Click here to join.

How Bankruptcy Changed One Couple’s Life For The Better

December 15, 2017

After a recent client meeting, I realized just how impactful financial conversations can be. It is truly amazing to see positive changes in a family’s life after what seems like a relatively straight forward, simple conversation. I met with this couple almost a year ago and they followed up a few times after that conversation with some quick questions. Then, 10-11 months went by and I saw them on my calendar. I was interested to hear what had developed in their life.

The situation:

She works for a big company that offers Financial Finesse services to their employees. He is a self-employed medical professional.

Back when the recession hit, his business took a turn for the worse. His patient visits declined annually and his expenses climbed. He kept taking on more debt as his rent increased and he tried to enhance his marketing efforts to attract new patients.

No savings and no debt, except…

When I first talked to them, they had no liquid savings and zero personal debt outside of their mortgage, but a mountain of business debt. We talked about their situation and their goals. They are very close to 60 and she would like to retire by age 65. He would love to work as long as his body will allow him to continue.

We looked at multiple ways for them to address their situation and with over $100,000 in business debt and a practice in decline, they were facing some less than pleasant potential solutions. Here are some of the ideas we bounced around prior to them making a decision and running with it.

  • Home equity. There was no reasonable hope the business could help them earn their way out of debt, so we looked at their personal assets as a potential source of funds to pay down the debt. Because the business had been “hemorrhaging dollars” for a number of years, they had exhausted all of their liquid finances along the way. The only real asset they had left was their home and they were considering a home equity line of credit to pay off as much of the business debt as they could. The downside of this option is they would end up collateralizing their home for business expenses.
  • Private lending. We looked at refinancing his debt through a private lending opportunity that was presented to him. The upside was that the interest rate was incredibly low. The downside is that the payments were still greater than the income his practice was generating.
  • 401(k) widhdrawal. Her 401(k) was gaining momentum and becoming a sizeable asset, with almost a $250,000 balance. We talked about the pros of taking a large hardship withdrawal from her plan – paying the debt off completely. We also talked about the downsides – a huge tax liability and needing to work an additional 5-10 years to recover the lost ground.
  • Bankruptcy. I very delicately waded into the waters of bankruptcy. They had very clear concerns. What would that do to their credit scores? What would that do to his reputation? He took on the debt, so isn’t he morally obligated to pay it off?

A textbook case

All of the debt was in the business name and not their personal names.  Much of the debt was owed to a real estate management company that itself was in bankruptcy proceedings. They had trepidations about this path, but from a purely financial viewpoint, their situation was a textbook case of when bankruptcy makes sense.

Those were the options we talked through and we also discussed the ongoing operations of his practice.  His biggest expense was rent and with a declining revenue stream, I questioned the level of rent. He was already a few steps ahead of me and was in the process of joining forces with other providers and moving into a space that was already operational and in use.

When talking specific numbers, this move lowered his rent by about 80% and made staying out of debt a relative certainty. Our first conversation and follow up emails confirmed that he was leaning toward moving into the new space and assessing his options for the debt once the move was completed.

Last week, we had a conversation about what they did and how they are progressing toward an eventual retirement. They let me know that they in fact went through with a Chapter 7 bankruptcy filing. It was approved and their business debt was forgiven.

On the personal side, they moved out of their house and bought a much smaller one since their kids are away at college or out on their own post-college. The net proceeds from the downsizing allowed them to reduce their mortgage payment by about $750/month and that is allowing them to build a substantial cash cushion and her to contribute the full $18,000 to her 401(k) as well as the $6,000 post-50 catch up contribution. He is going to fund a retirement plan for himself and we discussed multiple options for that during our follow up conversation.

The turning point

The moment that I will remember for a very long time in our most recent conversation was when they told me that they were totally opposed to pursuing bankruptcy because they felt morally obligated to pay off every penny of that debt. When I told them that they were a “textbook” example of bankruptcy, they looked at each other and in that moment, knew that they had to look at it. They went to a library and looked at a number of financial textbooks. When they read about bankruptcy for businesses, they saw themselves in a lot of the examples.

That quick conversation changed the trajectory of their financial future.

Why bankruptcy exists

The bankruptcy isn’t bailing them out because they have poor financial management skills. It’s helping them “hit the reset button” and get back to being the fiscally responsible couple they had been up until the recession and geography (their town is growing smaller by the year as people move to other local areas) hit with a force greater than his practice could handle. Bankruptcy exists to help people who have faced situations very similar to this. But bankruptcy can’t be a cure all.

Not a cure-all

Some people should absolutely not consider bankruptcy. Some of those types would be people who need a high-level security clearance, as bankruptcy could disqualify you from receiving that clearance level. Public figures and those in professions that require reporting/disclosing bankruptcy proceedings would be candidates for whom bankruptcy might not be suitable.

This couple’s debt was business related so that made bankruptcy a great option. Debts that are generally NOT able to be discharged in bankruptcy are IRS debt and student loan debt. It also wouldn’t be a great option for those who wouldn’t necessarily be considered “financial stewards” and have a lot of consumer debt because of living way beyond their means and not wanting to change that. If the behaviors that create a credit card heavy lifestyle aren’t changed, bankruptcy would only be a short term fix. It might even make things worse.

Not as bad as they thought

Postscript:  The new arrangement with the other practitioners is working extremely well. He has had four consecutive months of increasing revenue and can see a point in the next 6 months when he will be able to fund a retirement plan for himself for the first time in over a decade. The bankruptcy didn’t impact their credit scores much at all. He went from 805 to 750, but is now back at near 775.

For the first time since the recession started, they feel like they can breathe. The incredibly stressed couple I talked to initially had magically transformed into a relaxed, fun couple. There was laughter and optimism in our most recent call when during the first call all I heard was self-doubt, negativity and zero hope for the future. For me, seeing that I made a difference in the lives of a couple and the potential ripple as they interact with the rest of the world is exactly why I do what I do.

This post was originally published on Forbes.

How To Find A Bargain When Making A Big Purchase

November 10, 2017

Over the last few months, I’ve been on a quest to add a new skill into my life. Living in Maryland, near the Chesapeake Bay with marinas galore, and as a former boat owner – I decided that sailing is a skill that I should learn.

I grew up spending lots of time on the bay and lived on a boat for a number of years after my marriage ended. But I’ve always been a power boat guy — fire up the engines, get out into open water, throttle up and head to wherever we wanted to go. I always admired the simplicity and beauty of sailboats, but have never spent much time on them. I’m going to change that now. But, the journey hasn’t been easy.

Finding the perfect sailboat with a limited budget

I had some parameters that made buying my boat a bit difficult: I had a fairly low budget because I bought a house about a year and a half ago and used a large chunk of my savings for that. With a new mortgage and child support, cash flow is still relatively constrained. As excited as I am about learning to sail, I’m not willing to compromise my other goals like retiring on time in order to have a boat today.

So within my small price range, I got to work looking and I saw a lot of boats. Usually, my first thought was, “I can maybe make this work,” or “Is this a boat or a crime scene?” Everything I saw needed A LOT of work and I’m not opposed to that, but some were going to be lucky to not sink when they hit the water. None of them struck me as “this is the one,” though.

Adding up all the costs

I kept looking, kept searching, and then… boom: in the same week I saw 2 that were within my price range and felt like “home,” although one had a higher “sticker price” than the other. That’s when I started doing the full blown calculations of what this will cost me. Things I included:

  • the price of the boat
  • monthly cost of a slip at the marina
  • insurance
  • repairs & upgrades I’d want to do, etc.

After factoring in all of that, the full cost of each boat was roughly the same.

How to choose

So, it came down to preference – when I gave each boat a score from 1 to 100 based on what I wanted from an old sailboat, they both came in at about 90. Which is awesome because the others came in at around 10-15 on that 100 point scale! These were 2 serious outliers, and perhaps a bit mis-priced.

What I later discovered is that both were owned by people trading up to much larger and much more expensive boats and they wanted to unload their boat quickly to avoid paying for insurance and marina costs. With 2 boats that I valued equally, my “buying strategy” was to put in an offer a bit lower than the asking price on each one and see what happened.

What happened?

I lost out on one boat to another buyer and on the other, they gave me a counter offer, which I accepted. So by the time you read this, I’ll be out on the Chesapeake Bay learning how to sail. Wish me luck!!! I’m just hoping I keep my head low enough not to be hit in the head by the boom (some of my early sailing terminology at play here) as it swings from one side to another, knocked overboard and unconscious. If that happens and I’m out on the boat alone…this may be my last blog!

The big takeaway for everyone

When you are planning a major purchase, whether it’s a car, boat, household appliance, house, etc., the best way to go about getting the most value for your hard-earned dollars is to have a plan and have a strategy. I went into this with a definite maximum spending limit. It was low! Patience was required because I looked at over a dozen boats in person, and hundreds online and only found 2 that were acceptable given my goals.

Factor in all the costs

Don’t just look at the price of “the thing,” look at all the associated costs. For example, when my daughter bought a new car, her insurance rates went way up. When buying a major appliance, there are delivery and installation costs to figure in. Don’t forget closing costs when evaluating a mortgage.

Control your emotions

Don’t let your emotions make you “buy up.”  When looking at 1 boat that had a dirty smelly frat house vibe, I walked past another that had a “For Sale” sign on it & I looked at that one the next day. It was several thousand dollars above my maximum price, but it was NICE and my emotions told me that I could somehow make it work. I had to talk myself down from that emotion and stick to my plan. Emotions can sometimes be the enemy of good decision making.

How I kept my head in the game

In the end, I had a little index card where I wrote down the things that I wanted from a boat, including my maximum price and some things that would be deal breakers. When in doubt or I was tempted to stray from my plan, I’d look at my handy dandy index card and it would help bring me back to rational world. This way I know that I’ll always have smooth sailing, at least when it comes to financial side of this new hobby.

Want more helpful financial guidance, delivered every day? Sign up to receive the Financial Finesse Tip of the Day, written by financial planners who work with people like you every day. No sales pitch EVER (being unbiased is the foundation of what we do), just the best our awesome planners have to offer. Click here to join.


The Art Of Financial Trade-Offs: What Do You Value Most?

September 01, 2017

Last week, I found myself debating the best course of action for watching “The Money Fight” between Conor McGregor and Floyd Mayweather (spoiler alert: Mayweather won, to no one’s surprise). I’m a big fan of mixed martial arts (MMA), but for those who aren’t as into it, the appeal of the fight was that the biggest star in MMA (Conor McGregor) accepted a challenge from the biggest star in boxing (Floyd Mayweather) to go head to head in a boxing match, for what turned out to be Mayweather’s 50th win and last fight of his undefeated career.

I’m not a Mayweather fan (mostly because he glorifies a lifestyle of excessive spending, which is OK if you’ve earned $1 billion in your career like he has, but not great advice for most of his fans), so I was rooting for McGregor to win by early knockout. Despite the odds being stacked heavily in Mayweather’s favor, both men stood to win several million dollars.

In the fight world, this is a big deal. And, for me, it presented a challenge of how I wanted to watch the match — a challenge of both finances and fun. I had a few options here:

  1. Stay home and buy the pay-per-view at ~$100.
    Pros:
    – Watch in my PJ pants and eat/drink whatever I want.
    – Ability to adjust the volume to be whatever I need it to be.
    – No line at the restroom or waiting for a drink.
    Cons:
    – Unless I invited friends over and they brought food or beverages or chipped in for the PPV cost, this could be my most expensive option.
    – If something spectacular happens, there is no crowd yelling, which is part of the joy of watching with a crowd.
  2. Head out to a local pub that is showing the fight.
    Pros:
    – I can control the cost by limiting the number of cocktails and food I consume.
    – The bigger the crowd, the more entertaining the “oohs” and “aahs” and “OHMYGOD’s!” are.
    Cons:
    – It would be very crowded, so may be tough to get a table.
    – I’ve gone to watch big fights before and never gotten a table, and standing at the bar all night isn’t my favorite activity.
    – It could be a long night, so chances are that I would order food and a few beverages that could raise the cost close to the PPV cost.
  3. Skip the fight and read a good book, catch the highlights online the next day.
    Pros:
     – I get to read a classic and check it off my list.
    – It could be a nice, quiet night and I probably wouldn’t stay up till 1AM.
    Cons:
    – I wouldn’t get to experience the adrenaline rush and joy that I get when I see a great night of fights (although I find boxing incredibly boring after a decade-plus of watching MMA).

Making the trade-off

The trade-offs I had to make here, and that you probably face at times, had to do with several factors:

  • Cost vs. experience
  • How to spend discretionary dollars
  • Evaluating “needs vs. wants”
  • Probably a few others

At times, budgetary concerns are the deciding factor; other times, the fun and experience factor is what decides it. What I had to do in this situation was determine what my end goal was and then set a spending limit for my choice.

What I decided

I went with a hybrid of immersing myself in the experience while trying to limit my spending: I ended up going to a local pub with some friends, but first I made dinner for the kids and myself at home. That way I didn’t run up a big tab at the pub on food, but still got to see the fight without spending $100+.

I’m curious – how do others make this type of trade-off? I’d love if you would share your thoughts with me on Facebook or via Twitter.

Want more helpful financial guidance, delivered every day? Sign up to receive the Financial Finesse Tip of the Day, written by financial planners who work with people like you every day. No sales pitch EVER (being unbiased is the foundation of what we do), just the best our awesome planners have to offer. Click here to join.

How To Read The “Warning Label” Of Annuity Products

July 28, 2017

I love silly articles that I see on social media sites, and my kids and I love to look at warning labels for things that make us laugh. This article combines both of these highly entertaining things that I like. Since most warning labels are in existence because of someone actually doing the things that are being warned against, I always want to meet these people.

As entertaining as I find wacky warning labels, not all warning labels are intended to be funny. And actually, not all warning labels are actually warning labels, either. Some come disguised as sales literature for financial products.

Buyer beware

Case in point: I recently met with someone who had a 401(k) account from a prior employer, and her financial advisor had recommended that she roll it over into an equity index annuity with him. She had not decided whether or not to purchase the annuity before our conversation, thankfully. During our meeting, we looked at the “warning label” (aka the fee disclosures) for the proposed annuity to see if it was a good deal. Here’s what we found:

  •  10 year “surrender charge” — this means that if she wanted to get out of the annuity for any reason, including to change investments, advisors, or for poor performance, etc. in the next 10 years, she would have to pay a hefty fee to do so;
  • “Mortality & expense” fees — this is the insurance component, along with the sales charges (aka what the advisor would be paid,) and administrative fees;
  • “Management” fees — this was the investment component, which was in excess of 2.5% per year.

Finally, the track record of the investments inside the annuity was less than stellar, so she could potentially be paying 2.5% to actually lose money. If I could write a warning label for this annuity, I might have it say something like, “Product contains excessive fees,” or “Warning: your advisor might make more money on this than you do.”

After reviewing all of this information, she obviously decided to opt out of the annuity and transfer her prior account to her current employer’s 401(k) instead — knowing that her 401(k) had much lower fees combined with the ability to make changes to the investments without penalties, I think she made the right choice. The annuity’s “warning label” gave enough information about the product to make her consider another alternative.

Know what to look for

The lesson here is that investment products don’t come with explicit warning labels like hair dryers or plastic bags, but the language is there if you know where to look. Before you make any significant financial commitments, be sure that you fully understand the fine print on the warning labels, even if it’s not labeled as a warning.

Want more helpful financial guidance, delivered every day? Sign up to receive the Financial Finesse Tip of the Day, written by financial planners who work with people like you every day. No sales pitch EVER (being unbiased is the foundation of what we do), just the best our awesome planners have to offer. Click here to join.


How To Find A Missing Will

July 21, 2017

I recently had a chat with a friend who said he had a “simple question” about wills: His grandfather had recently passed away and he suspected that the uncle who had been living with grandpa may have been stealing from him, and perhaps destroyed the grandfather’s will as well. Now the uncle had plans to take significantly more than his “fair share” of grandpa’s assets in the absence of a will. The thing was, my friend’s grandfather had told him prior to his passing that he was leaving nearly half of his estate to my friend because of their special relationship and to make up for “past family wrongs.” His question was pretty much, “So…now what?”

A complicated question

Whew……that’s some kinda question! What could he do? And why did he think it was a simple question? The person he suspects of acting improperly (only a hunch with no tangible proof) clearly had access to the house & everything in it — he had access to the mail, he had access to any keys lying around, he had, in the words of so many detective shows, opportunity. Money seemingly is ALWAYS a motive. Well then, maybe there is something to the suspicion? Although, innocent until proven guilty still has meaning in my opinion. And now, after listening to so many podcasts about the wrongly convicted (Adnan Syed, Joey Watkins, Kalief Browder, etc.) – I’m starting to wonder about the “proven guilty” side of that phrase. But I digress…

What should he do?

I asked if he had talked to his uncle about the situation regarding the will. He had, and reported that his uncle said that he had looked everywhere obvious, but did not find a will, so he assumed that one did not exist. That either sounds, depending on your level of suspicion, completely legit or completely shady.

Then I remembered that his grandmother had actually passed 5 years prior and he said that SHE had a will, which means that will would be a matter of public record. I told him that he could go to the local courthouse and actually see her will, determine which attorney drafted it, and contact the attorney to see if he drafted Grandpa’s will too. Also, he could call the county’s Register of Wills to see if his grandfather had a will on record there.

The outcome

A few weeks later, I got an email from my friend with some follow up info. It turns out that Grandpa DID have a will, and it was drafted by the same attorney that had drafted his grandmother’s. What’s in the will? We don’t know yet, but at least my friend can rest easy knowing that his grandpa’s true wishes will be carried out rather than relying on his uncle’s assumptions (and still-to-be-determined trustworthiness.)

How to make sure this doesn’t happen to you

First, if you can’t find a will for a loved one that passes, definitely check with the county to see if perhaps a will is one file there, or call around to local estate planning attorneys. And while you’re at it, make sure a copy of YOUR will is on file with the county as well! The secondary lesson is that when you have your will drafted, make sure that there are multiple copies. Then, make sure that the people you love know where they are. It’s not likely that anyone in YOUR family would ever do what the uncle here might have been trying to do, but just in case…

Want more helpful financial guidance, delivered every day? Sign up to receive the Financial Finesse Tip of the Day, written by financial planners who work with people like you every day. No sales pitch EVER (being unbiased is the foundation of what we do), just the best our awesome planners have to offer. Click here to join.

Every Person Under Age 30 Needs To Read This RIGHT NOW

July 07, 2017

Over the past few weeks I have had the opportunity to watch my oldest child graduate from college and listen to a lot of conversations among her friend group about the terror they are experiencing regarding finding their first “real job.” Not a lot has changed since my friends and I graduated, at least in the terror department! Although, things are much different in the starting salary arena.

The first thing I noticed in their conversations about what they expect is that starting salaries today are what the next-level-up-in-the-organization’s salaries were when I was starting my career. And, as my kids would tell you, back when I graduated from college I still had to walk to work eating raw food until people invented the wheel and fire. But I digress.

As I listen to these young people debate the next couple years of their lives, I can’t help but wish for some magic power that would get them to listen to me about saving money. As they ruminate over how much they’ll make and what kind of apartment they can afford, all I can think about is the tremendous opportunity they have that will slowly buy surely whittle away that they’ll never get back if they don’t take advantage: time.

The mind-blowing power of compound interest

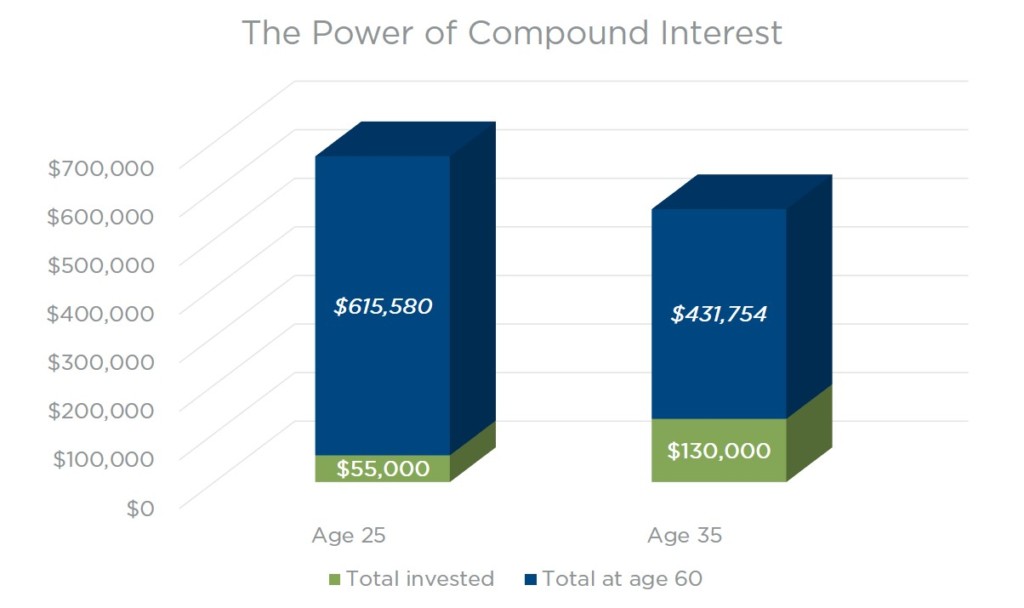
As a number crunching financial geek, I totally understand that compound interest works exceptionally well the longer the time period. And I vaguely recall seeing examples about how much it pays to save early, so during the course of a meeting with a 23 year-old new-hire this week, I went online and found this blog from Darwin’s Finance.

It shows what happens when a 25 year-old invests $5,000 per year (which is just about $200 per paycheck, which is easier to find than you might think) until age 35 and then stops (11 years, $55,000 total invested) vs. a 35 year old who invests $5,000 per year until age 60 ($130,000 total invested).  The net result still surprises me almost every time I look at it, and I’ve seen the results A LOT.

Assuming a constant 8% rate of return, the person who starts at age 25 reaches age 60 with a balance of ~$615,000 and the 35 year old who invests more than twice as much ends up at age 60 with ~$432,000.  That’s a HUGE difference, nearly $200,000. I shouldn’t be surprised by this result, yet I am every time I re-run the numbers. Starting earlier means you can save less (a LOT less!) and still have more! Mind: blown.

Take advantage of this!

For people who are early in their careers, I will make it a point to share this (and make sure that my daughter sends this to her friends on social media) and do everything I can to encourage them to participate in their 401(k) plans, open a Roth IRA, or simply save every dollar possible starting with their first paycheck.

The only negative I can find in these numbers is this: I showed this to a friend who is 40+ and has recently gone through a divorce and is starting all over again and he said the numbers depressed him. The good news is that even for the 40+ crowd (of which I’m a long-standing member), there is still time to save a substantial amount of money for retirement. I’ll address some “late starter” thoughts in a future post.

Want more helpful financial guidance, delivered every day? Sign up to receive the Financial Finesse Tip of the Day, written by financial planners who work with people like you every day. No sales pitch EVER (being unbiased is the foundation of what we do), just the best our awesome planners have to offer. Click here to join.

How To Protect Yourself In Case You Lose Your Pension

June 30, 2017

Over the last few months I have talked to a lot of people who are concerned that their company’s pension plan has changed for the worse, and I have a hunch the next few months will see more of the same. The state of Michigan is considering a complete overhaul to their teacher pension plan, placing the majority of the retirement savings burden on teachers, a trend I see only increasing as state and local governments face budget woes.

These are people from many different employers all across the country. Many others have seen an employer’s pension plan get frozen, terminated, or taken over by the PBGC. What was just a generation ago almost a “given” has become increasingly rare, and even when it exists there is ever increasing skepticism about the long term viability of the pension plan.

What can be done?

  1. If you have a pension…be thankful.
  2. Then, be prepared to see it change between now and retirement (even if you are retiring in the near term).
  3. Most importantly, take control of your financial life & get yourself in a position where no matter what actions your employer takes regarding the pension plan, you can retire comfortably.

OK, that sounds like reasonable advice, but how do you do that?

How to take control

In order to do it yourself, here are two things that will help you prepare:

Have a plan! Aka, think big picture.

  • Understand when you want to retire, how much you’ll spend, how much income you will have, and the financial resources available to you. (Get help from a financial planner if needed)
  • Run a retirement calculator to get a sense of where you are tracking toward your long term goals.  Determine how much you need to save between now & then.

Dig in to the details. This only takes a few minutes, so don’t be intimidated. But do make the time.

  • Understand your current budget and where your money goes. Where can you save more?  Where can you spend less?
  • Make sure your investment dollars are invested for optimal growth without too much risk. Do you have the right mix of stocks, bonds, cash and other assets?

When you have a fairly clear vision for your future, you can take actions that will help you reach your goals without feeling like you’re leaving your employer in control. Start with your big picture, dig into the details, and take control of your financial life. If your company pension goes away, gets frozen, gets taken over by the PBGC, or just never existed in the first place – it won’t matter because you will have prepared yourself for the future with or without your pension.


Want more helpful financial guidance, delivered every day? Sign up to receive the Financial Finesse Tip of the Day, written by financial planners who work with people like you every day. No sales pitch EVER (being unbiased is the foundation of what we do), just the best our awesome planners have to offer. Click here to join.

The Financial Services Industry Is Broken – Here’s How We Should Fix It

June 23, 2017

Along with being a financial planner here, each member of our team wears a bunch of different hats. Obviously, one of my other hats is a blogger. Another is being responsible for hiring new financial planners, where I have the opportunity to talk with incredibly talented CFP®’s from all over the country who want to work at Financial Finesse.

The reality of the situation is that even with a minimum of 10 years of industry experience and the CFP® designation, along with being wonderful human beings, only around 2% of those who apply for this role end up making it all the way through our hiring process. It’s astounding to me that I actually made it through the process and am working here.

Don’t tell anyone, but I regularly talk to planners who are smarter, harder working, more entertaining and much more photogenic than I am, and quite often they don’t get hired. There are lots of reasons for that, but that’s not the direction I want to take this post. Maybe another day…

What most financial planners do

The reason I talk about this is that the overwhelming majority of planners I talk to are in the business of giving world class advice to high net worth families when they apply to work at Financial Finesse, which is what I did prior to coming here. They are typically measured by the amount of assets or fees they collect and are tired of having to sell in order to also do financial planning.

For me, when I was working on a high net worth planning team, there was always a piece of me that thought, “The people we are working with are going to be just fine for the rest of their lives, even if they develop a bad case of ‘the stupids,’ while the people who most need our help can’t afford it and don’t have access to it. There is something fundamentally wrong with this system!” I interviewed three planners today who said something very similar. And that thought is what is driving them to look at us as a potential final career stop.

Working with the other 99%

Most of the employees I talk to in my role as a financial planner will never become a client in a high net worth planning office. Most would be happy just paying off their debt and having enough income in retirement to live a modest lifestyle. My guess (because I’m too lazy to do the math!) is that over half of the people I meet with are there to discuss either how to get out of serious debt or how to stop living paycheck to paycheck and maybe prepare for retirement or put their kids through college. These are the people who wouldn’t normally have access to decent financial planning guidance. And this isn’t isolated to the people I talk to – my colleagues say the same.

A recent Fed “Report on the Economic Well-Being of U.S. Households” reported that just under 1/4 of households can’t pay their monthly bills and almost half of households wouldn’t be unable to cover, with cash, an emergency expense of $400 or more. This information doesn’t surprise me, but it does get my hackles up a little bit about how messed up our financial services industry is.

These are the people that need help from our best and brightest planners. These are the people that our current system is leaving behind. These are the people that I wanted to help when I made the decision to work here.

A new branch of the industry

The good news is that these are the people that I’m helping today. Financial Finesse was founded on the belief that all Americans, regardless of income or net worth, deserve access to excellent financial planning guidance. That’s the vision that guides us. And we are actually excited to see more competitors in our space. Employers are catching on that providing a workplace financial wellness benefit is good for employees and it’s good for the bottom line – if you don’t have a financial wellness benefit at work yet, chances are you will. And that’s a good thing. I firmly believe that our industry will revolutionize the way traditional financial services are offered in the future.

I only wish that every employer in the country would work with us so that I could help everyone. Since I can’t clone myself, I try to at least hire others who have that same burning passion to help those who need it the most. Our internal motto and rallying cry (what I like to say is our true mission), is that we are “changing f’ing lives.” And that’s what we’re doing – one person, one family at a time.

What’s in it for you

What does this have to do with your own personal financial situation? Well, if nothing else, know that we feel your pain – getting unbiased answers to your questions is truly a challenge in today’s world. But if you do have access to a financial wellness benefit at work, USE IT. It’s there to help you and it’s not just for people who are in crisis. In fact, the best time to use it is when you’re not, so we can help make sure you’re ready when the next crisis hits.

Want more helpful financial guidance, delivered every day? Sign up to receive the Financial Finesse Tip of the Day, written by financial planners who work with people like you every day. No sales pitch EVER (being unbiased is the foundation of what we do), just the best our awesome planners have to offer. Click here to join.

Here at Financial Finesse, we believe strongly in the importance of workplace culture and the power of doing well by doing good. This article is the fifth in our week-long series of posts where we highlight a specific part of our company culture that helps to make Financial Finesse one of America’s best places to work. This is just one part of our celebration of recent recognition by Inc., who listed us as one of the Best Workplaces in 2017 and Entrepreneur, who named us to the Small-Sized Companies: The Best Company Cultures in 2017 list.

My Plan to Live in 43 Cities and Make Money Doing It

June 16, 2017

This spring has been an absolute blur for me: my daughter graduated from college, then six days later, my middle guy graduated from high school. Two days after that, my youngest started taking finals in his first year of high school. Granted, all I had to do was show up & root them on, but it’s been super busy and a bit emotional too. 

Any day now, my daughter will receive a job offer and become a full-fledged adult member of society, when I swear it was only a few days ago that I held her hand and walked her down the hallway to Ms. Linzey’s kindergarten class… Now I’m facing the fact that in three short years, my youngest will be a high school graduate, moving on to the next phase of his life. It’s time for me to ponder what I want to do once the kids are gone. 

The last two decades of my life have been way more about them than it has been about me, and for that, I’m a much better and happier person. But now that it’s time to start thinking about my next chapter, I realize that what I have jokingly referred to as my “Professional Hobo Plan” (PHP) is actually something I might be able to pull off.

Becoming homeless by choice

One of the beautiful parts of working at Financial Finesse is that in order to do my job, all I really need is a telephone, a solid internet connection and a nearby airport. From what I’m told, they have those three things pretty much everywhere now, which means that I can work from almost anywhere. So that’s what I plan to do. 

My current game plan for my PHP is to move around to a number of different cities for some yet to be defined period of time, long enough for me to feel more like a local than a tourist. Right now my list of places sits at 43, but it grows once in a while. Some places, like New York City, might require a 3 – 6 month stay (or longer) in order to learn the city like a local, while some, like Portland, Maine, might be more like a 2 – 3 week engagement. In between cities, I’ll come back home to Baltimore to see friends and family – and anyone is welcomed to come visit me during my travels. 

Living in 43 cities without going broke

This sounds like a cool plan in theory, but the question I’ve wrestled with was how to pull it off without going broke. I already went through a long and costly divorce and am not where I projected I’d be financially at this age, so I need to make up ground rather than lose ground toward my longer term goals. This is when a few conversations over beverages, random thoughts in the shower, time alone on a plane/train/automobile and some time playing on the internet gave me some ideas about how to fund this and even make it a positive impact financially. 

Making it a financial win

While going through my divorce, I actually lived on a boat for 3 – 4 years before moving back on to land and selling the boat. I moved primarily because my kids didn’t love winters on the boat, but once they’re gone, I can easily buy an inexpensive boat, which are in great supply with low demand in this economy, and spend my Bmore time on the boat. This would give me a place to stay while I rent my house for a 2 – 3 year window. 

I’ll have my Financial Finesse paycheck along with rental income, while my living expenses will consist of a cheap rickety boat & slip fees that are less than my property taxes. I figure I can save my entire income for a few years if my rental income is steady. And as an added bonus – in some cities there are opportunities to get paid to do house-sitting! Who knew??? I’m picturing a house-sitting income in one city that might pay for a non-house-sitting temporary home in my next city, so my effective cost of on-the-road housing is negligible, while my Bmore housing cost is a net positive cash flow. And, I get to see every cool city in the US and learn them like a local. I may even get a book written along the way…

Making the most of a flexible job

That’s the dream, the plan, the working model currently. I’m not sure if I’ll pull the trigger on this plan in 3 years or not. Life has a way of throwing things at us that make plans change. But if I do, it’s completely because this work-at-home when not traveling out to client sites allows me a lot of flexibility and freedom.  And — if I can get the US plan worked out – I could potentially expand the model to include some international cities. That might take more coordination because I do work at our client sites fairly often, but I have a few dozen US cities to hit before I start putting my International Hobo Plan (would I get sued if I call it my IHoP idea?) into action.  

Want more helpful financial guidance, delivered every day? Sign up to receive the Financial Finesse Tip of the Day, written by financial planners who work with people like you every day. No sales pitch EVER (being unbiased is the foundation of what we do), just the best our awesome planners have to offer. Click here to join.

How Would You Answer This Million Dollar Retirement Question?

June 09, 2017

A recent article in the Wall Street Journal asked a question that has led to one of my favorite conversation starters, both with clients and over beverages at my local watering hole: “Would you rather have $1 million or $5,000 per month in retirement?” To me, the way a person answers that question tells me a lot about how their mind works around money. So far, the answers I get are split about 50/50. Here’s what I’ve learned:

I’ll take it all right now, please.

Those people who choose the lump sum tend to have a strong belief in their ability to be fiscally sound. When asked what they’d do with the money, they typically say that they would pay down every penny of debt, make a luxury purchase or two, then live fairly frugally to preserve the remaining money, while investing it to get some growth. Their hope is to be able to grow that initial lump sum well beyond the starting amount and also do some good in the world.

I’d rather keep a steady paycheck.

On the other hand, the people who say they’d rather have the monthly income tend to be wary of becoming one of those tragic stories about people who “had it all” and then blew it. They feel like they can live on the monthly income with ease and save a portion of it for future generations or charitable work. The WSJ goes into the psychology of this choice, which is something called “the illusion of wealth” versus “the illusion of poverty,” but you’re better off just reading the article to understand that one better.

Are you focusing on the right number?

Why do I mention this debate? So many people that I have talked to regarding retirement are completely fixated on getting to some “magic number” in their 401(k) before they’ll feel safe to retire. When I meet people who are locked in on needing X number of dollars in order to retire, they are almost always already in excellent shape for retirement. Why? I find that they’ve been so laser focused on the dollar value of their accounts that they haven’t really thought about the monthly income that the portfolio could generate.

In many cases they’ve saved enough that they can afford to have a higher monthly income than their current income! I can’t count the number of times I’ve told someone that they can walk back to their desk because they are choosing to, not because they need the paycheck.

The number that counts.

When we prepare retirement projections, the most important number – in my opinion – is the monthly income that a person will have from all sources (Social Security, pension, investment accounts, retirement accounts, etc.) during retirement.  After all, most people have a lifestyle that requires a rather consistent monthly income.  If that income, plus some, can be replaced today – work truly becomes an option, not a requirement. 

Find your number.

What can you do? Run retirement projections at least annually. This is probably the most important thing anyone can do to track their progress toward financial security. After a few years, your projections should show a trend. If you’re doing things right, you’ll see that trend improve with each year. When it doesn’t, you can decide what actions to take in order to get the trend line back to being a positive. Regardless of your stance on the question of a big lump sum vs. a steady monthly income, running a projection to see how much income you can expect to have in retirement will help you determine a lot of financial decisions between now & then. To steal a line from Nike: when it comes to running retirement projections, JUST DO IT.

The Thing That Millennials Are Getting Right About Money

June 02, 2017

If you know me, you know that it’s no secret I have a strong dislike for breaking down financial statistics by demographics. Yes, I realize that there are some benefits to looking at trends this way, but there’s a little part of me that bristles whenever we start pointing out the differences in people, especially in today’s less than harmonious political climate.

One of my guiding life principles is that people are people, and we are largely the same regardless of our age, gender, race and other demographics. We all want to see our friends, family and loved ones succeed and we all want to enjoy our lives. And while it may seem naïve and idealistic, I’d like to see those who hold opposing points of view start from a point of commonality in their discussions rather than defending their differences.

So while it’s clear that I am not a fan of discussing differences, I’m about to…

The stereotype

One of the things I often hear is that this current generation of millennials doesn’t seem to view working and saving for retirement the same way that older generations do. A common gripe of gen Xers and baby boomers is that millennials (I really despise that label, as do most of the members of that generation whom I know) are lazy slackers who want to be paid well with fancy titles before they ever accomplish anything.

“Those darn millennials…”

It’s easy to view the next generation as not being as hard working and ambitious as your own generation; I’ve seen that with the way my grandfather talked about my father’s generation and how my generation talks about millennials. Their music is too loud, they don’t work as hard and their standards aren’t as high. It seems like each generation has the same complaints about the succeeding generation as the prior generation had about them. There’s some beautiful irony there.

Surprise! They’re getting this one right

However, I recently came across a very interesting article about the financial behaviors of the millennial generation, which got me to thinking that maybe their bad rap is not justified. The article points out that it may be true that millennials aren’t saving as much for retirement as other generations may be, BUT – and this is a huge point – they do have a higher overall savings rate than other generations. On average, they are saving 19% of their income with over 1/3 of them saving in excess of 20% of their incomes. That’s absolutely incredible! Well done, millennials.

Saving for something else

The thing that irritates older generations though might be that the savings aren’t earmarked for retirement. The savings figures are high, and the money saved is often used for current lifestyle considerations such as travel, fitness & health, and dining out. They are spending money on experiences today rather than building up a gigantic nest egg for the future. Retirement isn’t at the top of their list of reasons to save.

The wisdom of those gone before

While older generations may view that as less than ideal, perhaps it’s just where they are considering their stage of life. And, perhaps it’s wise and it’s something learned from listening to and learning from prior generations. I have heard many older relatives say that they wish they had traveled more extensively when they were younger so that they had more energy and stamina, and their bodies didn’t rebel against long hikes through foreign cities.

A different perspective

Maybe, instead of seeing this generation as snowflake slackers, we should maybe try to see them as incorporating the wisdom of prior generations and putting it into action. Is it possible that millennials are more financially savvy and more mindful of the important things in life than they are being credited for? It’s something to consider.

If you’re a millennial reading this – great job saving so much of your income. It’s a fantastic habit that should translate to a nice bucket of money if/when you actually do retire. If you’re not a millennial and you’re reading this – I’d like to suggest that you maybe try to be more like a millennial and drive your savings rate up above 20%. As they’re learning to listen and implement wisdom from older generations, let’s learn from them as well.


Follow This One Simple Rule for a Secure Retirement

May 26, 2017

While I was taking pictures of my middle guy and a whole bunch of his friends right before their senior prom, I was having a conversation with one of the other kids’ fathers. The inevitable conversation about what kind of work we do came up and he was, at one point in his career, working for a large accounting firm that has a wealth management arm. When he found out I was a financial planner, he shared a story about his colleague who ran that part of the business and had built himself a very nice retirement portfolio. My prom-dad-buddy asked him what the secret was that he used to grow his wealth & that of his clients.

The answer was simple: “Always live on your income from 5 years ago.”

When I heard that, I thought it was an interesting concept. If someone is accustomed to pay increases on an annual basis, this allows for a considerable amount of savings each year. This is a concept/theory that I had not heard before playing amateur photographer at prom time. But, it’s consistent with my very incredibly simple rules for personal financial management:

  • Spend less than you make
  • Don’t take on high interest debt
  • Save 10% or more of your salary
  • Always live on your income from 5 years ago

How it works

At a 3% pay increase, someone who earns $50,000 this year would earn $57,963 a mere 5 years later. Living on the original $50k would allow that individual to save almost $8,000 (probably closer to $5,000 after taxes & benefits) that year. If that same person contributed 10% of their income ($5,793) to their 401k – that’s one heckuva combined savings rate (>18%) before we even consider an employer matching contribution or account growth. If that pattern is repeated for a couple decades….retirement starts to look awfully secure. (I tried to do the math, but it got complicated. Suffice it to say, we’re talking about doubling your savings or more with this method)

There are a whole lot of very simple methods for becoming financially secure and these are just two of them. Managing your financial life isn’t as complicated as a lot of people make it sound. I’m a financial planner who hates the term “budgeting” because it sounds so restrictive and so much less than fun.  I prefer to have a couple of quick & easy spending guidelines instead, like these grumpy old man rules.