How We Are Deciding Which Spouse’s Insurance Plan To Use

February 06, 2025

My husband recently changed careers and is starting with his new employer at the end of this month. We’re all very excited about the transition as a family, but we have a very important decision to make: are we going to stay covered under our current health insurance plan that I have through work or are we going to move over to his plan? Or should the kids join my husband on his plan while I stay on my own? Decisions. Decisions.

How do you decide whose health insurance to use?

When both partners have benefits through work, it’s a good idea to re-examine your family coverage each year. Here are some of the things that we are considering as we decide which benefits to choose. These questions might trigger some points that are important to you and your family as well as you make your decision whether to stay put or move on to your spouse’s plan:

Questions to ask

  1. Are our current doctors considered in-network under my husband’s plan (especially the kids’ doctors)?
  2. Do my husband and I like the primary doctor options who fall in-network under his plan?
  3. If my husband has employee-only coverage at work, does his employer cover his monthly premium? (mine does)
  4. How do the monthly premiums and deductibles compare to what’s available under our current plan?
  5. Once we hit the deductible, how much is our coinsurance (the percentage we are responsible for paying)?
  6. Is a high deductible health plan (HDHP) an option with his employer and how much, if anything, does his employer contribute to a health savings account on his behalf?
  7. Are there any upcoming specialists we’ll need to see? Surgeries any of us will need? If so, are they covered? And how much would we be responsible for paying?
  8. Are there any specific medications we know we’ll need that are not covered under my husband’s plan?

These are some of the things we’ve started to consider. Thinking through your situation and coming up with your list of questions like these, or points that you want to be sure you address, will help you choose the coverage that best meets your needs. Be sure to break down the costs and compare apples to apples when choosing the right health insurance plan and steer clear of common mistakes that are often made during enrollment.

When you need to switch mid-year

It’s important to note that our decision happens to fall during my open enrollment period at work, but if it were outside of my company’s open enrollment period, my husband’s change in employment status (and thus his new eligibility to be covered under a health plan) would be considered a qualifying life event and we’d have a short time frame (typically 30 days) to make changes to our health plan.

The Impact of Artificial Intelligence on Financial Decisions for Retirees

September 05, 2024

This essay explores the profound implications of artificial intelligence (AI) in reshaping the financial landscape for retirees. Artificial Intelligence refers to the simulation of human intelligence in machines…

Think Tank Research Best Practices

June 03, 2024

In our Workplace Financial Wellness in America report, we saw a substantial increase in the percentage of workers
who said they were experiencing high or overwhelming levels of financial stress…

Workplace Financial Wellness in America: A Year in Review

May 31, 2024

Abstract:

Looking back, 2023 was a year of two opposing stories—and two different economies. For investors, stock market gains helped propel savings balances to levels not seen for several years. By contrast, financially vulnerable workers continued to feel the economic pressure of persistent inflation and higher federal interest rates. These factors have a tremendous impact on financial resilience and retirement preparedness, as well as financial stress levels. Given the strong relationship between financial stress and job satisfaction, mental and physical health, and productivity, the argument for offering financial coaching that helps American workers improve in these areas remains clear.

To read the full Report, download now.

  • Download

Financial Wellness or Cash Flow Band-Aid?

June 26, 2023

Abstract:

This white paper explores the impact upon the overall financial wellness of workers when using various financial point solution benefit programs such as earned and early wage access (EWA), buy-now-pay-later (BNPL), and small dollar employer loan programs. It also explores the pros and cons of point solutions and potential positive or negative effects on employees’ overall financial well-being. Analysis and discussion include whether point solutions provide a meaningful “financial wellness” benefit as often touted, or if these limited benefits are more of a short-term fix approach to serious financial challenges faced by workers: pervasive consumer debt, low wages, and cashflow mismanagement. The paper concludes with a comparison of point solution outcomes versus a holistic financial coaching and wellness approach.

To read the full Report, download now.

  • Download

2022 Workplace Financial Wellness in America: A Year in Review

May 23, 2023

Abstract:

The state of financial wellness of the U.S. workforce fell in 2022 as high inflation and economic uncertainty raised employee financial stress to levels not seen since the Great Recession. The rise in financial stress has contributed to declines in overall wellbeing as self-reported mental and physical health have fallen to their lowest points in two decades. Employees that engaged in their financial coaching benefit made substantial improvements in financial behavior; those that engaged with a live financial coach fared even better than those that engaged exclusively with a virtual financial coach. Working with employee resource groups (ERG) to deploy financial coaching benefits tailored to minority experiences has proven to be effective at increasing employee engagement and improving financial outcomes.

To read the full Report, download now.

  • Download

Infographic: Coach to Advisor Case Study

April 03, 2023

How one family brought their Financial Coach and Financial Advisor together to optimize outcomes.

Think Tank Bulletin: Student Loan Debt on the Workforce

March 21, 2023

Currently, an estimated 43.5 million Americans carry over $1.7 trillion in student loan debt—an average of over $37,500 per…

Race and Financial Stress Special Report

October 25, 2022

Executive Summary:

The racial wealth gap in America has garnered much attention as part of the fight against social injustice. It is highly encouraging to see many of our partners that have not only publicly pledged their support in this fight, but are actively searching for ways to make tangible headway within their organization. Many are leaning on their financial wellness benefits to do just that, as they understand that improving the financial wellness of their most vulnerable employees will, over time, drive results in this quest for financial equity amongst the races.

In this special report, we’ll explore:

  • The current racial disparities in financial wellness
  • What role income plays in these disparities
  • How financial wellness is successfully driving improvements to narrow the gap
  • Ideas on how to improve financial wellness disparities within your organization

To read the full Report, download now.

  • Download

2021 Financial Wellness Year in Review: A Q&A with Financial Finesse founder and CEO, Liz Davidson

June 20, 2022

Abstract:

This Q&A is designed to provide quotable commentary on Financial Finesse’s 2021 Financial Wellness Year in Review.

To read the full interview, download now.

  • Download

2021 Financial Wellness Year in Review

June 20, 2022

Abstract:

Workplace stress has risen steadily for over a decade, and with the help of a global pandemic has reached a tipping point in 2021. Workers are increasingly expecting more support from their employers, and they are willing to change jobs to get it. To compete for talent, employers must shift their approach to benefit design and corporate culture to accommodate the new workforce. This report examines the divergence in financial wellness priorities that is signaling a shift in the employer-employee relationship and offers guidance for how employers can handle this workplace revolution.

To read the full Report, download now.

  • Download

2020 Financial Wellness Year in Review

May 25, 2021

Abstract:

The state of financial wellness of the U.S. workforce improved in 2020 despite the economic challenges created by the COVID-19 pandemic. The greatest improvement occurred in the areas of cash flow, debt management, and homebuying. Employees that maintained a handle on cash flow and an emergency fund prior to 2020 fared best during the pandemic, leading many employers to add financial resiliency to their list of key focus areas in 2021. As concern for racial financial equity and equality grows, we expect to see more emphasis on diversity and inclusion (D&I) in workplace financial wellness initiatives in the coming years.

To read the full Report, download now.

  • Download

August 2020 Engagement Study

March 15, 2021

Learn how financial coaching influenced coronavirus related distributions in this study conducted by Financial Finesse on behalf of a large, midwestern building supply manufacturer.

What’s it really like to work with a financial coach?

March 11, 2021

Until they’ve tried it, your employees will never know; and not knowing may be keeping them from engaging with a benefit that could literally change their lives. 

Nearly 2 in 3 adults (64%) say that money is a significant source of stress in their life

We know that Americans are dealing with significant levels of financial stress, in many cases exacerbated by COVID-19. According to the American Psychological Association, “Nearly 2 in 3 adults (64%) say that money is a significant source of stress in their life, and around half of adults (52%) say they have experienced negative financial impacts due to the pandemic.”[1]

We also know that talking with a financial coach can improve financial stress levels considerably. For example, the percentage of financially suffering employees (i.e., those with an initial financial wellness score of less than 3.0) with high or overwhelming levels of financial stress fell from 70% to 41% after talking with a financial coach as part of their financial wellness benefit.

So how can we get employees ‘over the hump’ of not knowing and get them comfortable enough to call a coach? I asked our coaching team which myths or misconceptions they believe may be holding employees back. Allow me to bust them.

Myth #1 – A financial coach will try to sell me something.
While many financial professionals are compensated for selling financial products, this is not the case at Financial Finesse. Our company is independent and not affiliated with any other financial institution and our coaches do not sell or manage any financial assets.

Myth #2 – A financial coach will judge me or talk over my head.
Fear of judgment is universal, which is why we seek coaches that have first-hand experience with common financial challenges and screen for empathy and emotional intelligence (EQ).

Fear of judgment is universal

Our coaches are motivated by helping employees make progress, no matter what their starting point. In every conversation, they aim to make financial concepts easier to understand and to build rapport. To get a sense of who is on the other end of the line, employees can “meet” our coaches here. 

Myth #3 – A financial coach is not trained to deal with my problems.
Some may think their issues are too simple to merit a call or too complex for us to help. Our coaches address the full range—from fundamentals to complex topics—every day. If an employee needs advice (we provide coaching only), for example on taxes or investing, we can help them find someone through objective screening—we do not have a referral network or any affiliation with any providers.

Myth #4 – A financial coach expects me to have my finances in order before we speak.
Our coaches are happy to help employees get started—no prep work required. We hope the first call is not the last. That’s why we encourage employees to reach out to get the ball rolling.

Myth #5 – A financial coach will share my information with my employer.
This one simply isn’t true. Our coaches adhere to a strict code of confidentiality and never share any information with employers as it relates to their employees’ financial health.

Myth #6 – A financial coach can only discuss benefits offered by my employer.
While our coaches often help employees get the most out of their benefits, they are by no means limited to benefits-related questions. They can help with any financial concern.

We know that the more employees interact with our coaches the more their financial wellbeing improves, but getting first-time users started can be a challenge. By understanding their concerns, you can develop a communication strategy to address them head-on, encouraging engagement and changing lives—a win-win for any organization.

[1] https://www.apa.org/news/press/releases/stress/2020/report-october

COVID-19 Special Report: The Impact of a New Normal

May 13, 2020

At the time of this report, America is battling the COVID-19 global pandemic. In response to social and economic pressure, many employers have adjusted the way they do business, including implementing social-distancing protocols, work-from-home arrangements, and in some cases workforce reductions. Virtually all employees, to one degree or another, are experiencing adverse effects to their financial health. These effects are often hardest felt by those that are least prepared to handle them.

Although there is a tendency to look at the workforce as a single unit, employers increasingly need to segment their workforces from a financial wellness perspective because of the disparity in financial stress and behavior that exists among coworkers. In our 2016 ROI Special Report, we introduced a method of segmenting the workforce into five levels of financial health based on employees’ financial wellness scores: Suffering, Struggling, Stabilizing, Sustaining, and Secure. This report includes more detail on each segment.

Q&A with Financial Finesse CEO, Liz Davidson

May 06, 2020

Financial Finesse’s 2019 Year in Review Research Study & The Impact of a New Normal Post COVID-19

View the entire COVID-19 best practices abstract “The Impact of a New Normal” here.

1. Question: What were the most significant takeaways from the 2019 Year in Review report? 

Answer: For this year’s report we looked at how engagement in online, group, and individual learning sessions influence change in financial wellness as measured by the Financial Finesse Financial Wellness Score. The results were astounding.

Employees that engaged in group learning improved their financial wellness score on average 1.11 points, 40% higher than the 0.79-point average improvement by those that engaged exclusively online. But it was the employees that followed the best practice model and engaged in all three forms of learning that topped them all, improving their financial wellness score on average 1.44 points, outperforming group learners by 31% and online-only learners by 83%.

This improvement in financial wellness also translated into improvement in benefit participation. Employees that engaged in the best practice model had a 43% higher retirement plan deferral rate and an 81% higher annual contribution to a health savings or flexible spending account than employees that only engaged online. 

We also found that the greatest net improvement—which is the difference between improvement by those that engaged in the best practice model and those that engaged exclusively online—occurred among employees with the lowest levels of financial health. What is even more remarkable is the speed of improvement. Financially stressed employees exhibited the greatest degree of improvement in the shortest amount of time across all levels of engagement.

2. Question: What can employers leverage from the 2019 Year in Review report to help employees navigate the financial impacts of COVID-19? 

Answer: In the wake of the COVID-19 pandemic, we are seeing signs of increasing financial stress associated with the stock market and U.S. economy manifesting itself as a lack of trust in sources of financial guidance and concern for not reaching future financial goals. When considering the relationship between physical health, workplace productivity, and financial stress, this should have employers’ attention. The good news for employers is that the best practice model yields the greatest improvement in financial wellness for the most financially stressed employees in the least amount of time. These results could not have come at a better moment in history.

As the pandemic persists, we expect to see a shift toward lower levels of financial health across the global workforce. Given the strong relationship between financial health and employment cost, we encourage employers to focus their COVID-19 efforts on providing financial resources and support to their most financially stressed populations first. This population can be defined through a workforce financial wellness assessment, a demographic analysis, or by measuring financial stress metrics such as retirement plan leakage, garnishment, or benefit utilization. Once the at-risk population is defined, consider offering ongoing financial coaching delivered through a multi-channel model if possible. 

3. Question: What drives the trend of end-users in the lowest tiers of financial health exhibiting the greatest level of improvement in the shortest amount of time?

Answer:  The emotional courage it takes to confront serious financial issues is significant.  Finances still remain taboo, especially for those who are struggling financially, and there’s often a sense of shame or helplessness they have to overcome.  The best practices model is well suited to mitigate that, because it is set up to reduce barriers as a financial wellness benefit that can be accessed however employees feel most comfortable, and then migrate to ongoing financial coaching when they are ready.  The message they get is “We are all in this together.  Everyone has financial challenges.  You are not alone and there is nothing to be ashamed of.”  That alone makes a huge difference.  

Then when you consider the small wins in finding ways to reduce expenses by getting better deals on essential items, get credit relief or lower interest rates, begin the process of starting an emergency fund, can make a huge difference to financial stability, it makes sense that those who struggle most would improve the most with a model that provides unlimited financial coaching through multiple channels.  

4. Question: On average, which aspects of an employee’s financial wellness improved the most under the best practices model?

Answer: On average, employees that engaged in the best-practice model for five or more years showed a 1.59-point improvement (on a 10-point scale) in financial wellness score. The greatest net difference between improvement among employees who engaged exclusively online and those that engaged in the best practice model occurred in the areas of retirement planning and investing. Employees that engaged in all forms of learning also had a 43% higher retirement plan deferral rate and an 81% higher annual contribution to an HSA or healthcare FSA than employees that engaged exclusively online. They were also more likely to have a handle on cash flow, have an emergency fund, pay bills on time, be comfortable with debt, and pay off credit card balances in full. 

5. Question: How do you anticipate COVID-19 may alter the traditional compensation and benefits structure most workplaces have become accustomed to? Do you anticipate a potential or temporary decrease or suspension of benefits like 401(k) matching, PTO, etc., as employers explore potential cost-savings strategies to avoid having to layoff or furlough employees? 

Answer: Many employers are considering any practical cost-saving measures to stay afloat during this crisis. However, rather than decreasing or suspending benefits that impact some, I believe we will see a strategic refocus of attention and funds, where available, towards benefits thought to be more flexible and impactful across the board, like HSA’s for example. 

That said, I believe COVID-19 will cause a major mind shift in how we think about employee benefits, in line with human-centered design principles, where the focus shifts from the benefits themselves to the employee’s individual financial needs, integrating benefits in a way that best meets their financial security. This includes:

  • Increased personalization of benefits so each employee can design their own benefits package that best meets their needs, with the help of digital and phone based financial wellness platforms that guide them through the decision-making process. 
  • Increased focus overall on workplace financial wellness as an employee benefit. Employers are actively looking for support in helping their employees through COVID-19 financially and I believe these efforts will quickly morph into a much deeper commitment to financial wellness as a standalone benefit. Our business more than doubled in Q1 2020 vs. Q1 last year and is only gaining momentum as more employers look for proven and cost-effective strategies to help promote their employees’ wellbeing and financial security. 

6. Question: According to PayScale, the gender pay gap has improved 7% since 2015. Why do you think the gender gap in financial wellness continued to widen for women in 2019 despite a narrowing of the gender pay gap over the last several years? 

Answer: Historically, the gender gap tends to widen in periods of economic expansion and narrow in periods of economic contraction. This has held true throughout the duration of our research. Based on the data, men tend to be more confident and aggressive in their investment strategies during bull markets, which puts them in a better position financially at the time, but also creates more risk in the event of a market downturn. Women, on the other hand, tend to be more conservative, but also more resilient and take a more active role in managing their finances in a down market. Since 2019 was a strong year for the market and economy overall, the gender gap widened. We fully expect it to narrow post-COVID-19. Please note, the narrowing is not necessary a good thing as it represents the “gap” not “absolute” financial wellness. In tough economic times, both men and women tend to regress financially, women just regress at a slower pace. 

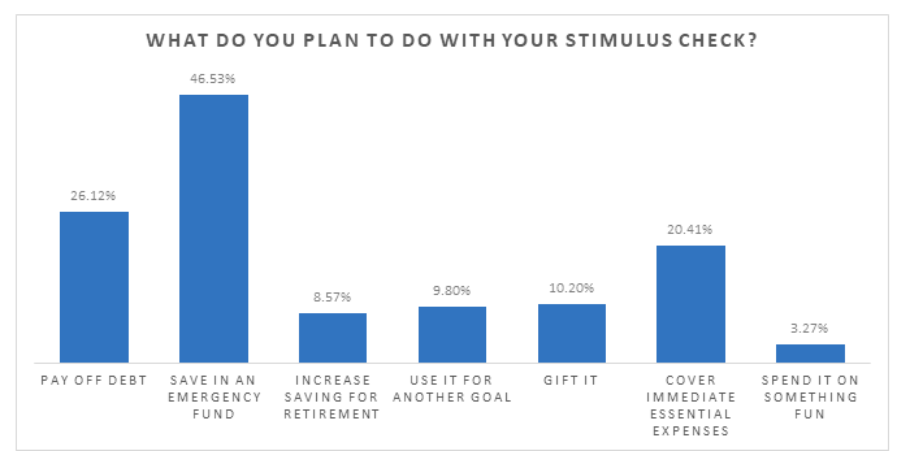
7. Question: How are employees planning to utilize their COVID-19 economic stimulus checks?

Answer: As part of our ongoing COVID-19 relief efforts, Financial Finesse hosts weekly webcasts aimed at helping employees navigate the day-to-day financial changes and decisions we’re all facing. In order to make these webcasts as relevant as possible, we created a follow-up survey and shared it with the thousands of employees who attended. One of the questions we asked was “What do you plan to do with your stimulus check?” Surprisingly, the majority of respondents that received a payment (47%) plan to put it toward an emergency fund. Only one in five (20%) indicated using it to cover immediate essential expenses. While there is no such thing as good news when it comes to COVID-19, we were excited to see most employees proactively saving their stimulus check versus reactively relying on it to cover immediate essential expenses. 

2019 Financial Wellness Year in Review

May 06, 2020

The state of financial wellness held constant, but the typical employee engaging in a financial wellness benefit is gradually looking younger and more masculine. Improvement in employee financial behavior has been subtle but includes fewer reporting they carry a balance on their credit cards and more indicating they check their credit report at least once a year. The type of engagement—e.g., online, group, individual, or all three—also influences the degree of improvement, with those engaging in all three types garnering the highest levels of improvement. As demand for financial technology coupled with live financial coaching increases, we expect greater improvement in workforce financial wellness for years to come.

To read the full Report, download now.

  • Download

VIDEO: How to Help Your Employees Through the COVID-19 Financial Crisis

March 25, 2020

VIDEO: Your COVID-19 Financial Survival Kit

March 25, 2020

FAQs from Your COVID-19 Financial Survival Kit Webcast

March 25, 2020

You may have joined our recent webcast titled Your Covid-19 Financial Survival Kit. We had a lot of questions come through during the sessions so we want to share the commonly asked ones, with their answers! Our facilitator, Bruce Young, CFP, has provided written answers below.

Take a look at the different topic areas, and for more resources see the banner on the home page of your Financial Finesse Hub

401 (k)

Q) Should I keep funding my 401 (k)?

A) Yes! you are buying low and you don’t want to miss out on matching funds if it’s available to you.

Q) Should we lower the amount we are contributing to our 401 (k) for the current time period?

A) Unless you need to redirect funds to beef up your emergency fund, you should avoid lowering your 401 (k) contribution because you are now buying low and can take advantage of dollar-cost averaging.

Q) Is this a good time to increase my 401 (k) payroll deduction?

A) Yes, if you have an emergency fund already then this is a great opportunity to be investing more in your 401 (k) while the market is low.

Q) I am within 11 months of retirement – should more go to fixed income (money market, CD’s) or leave a portion to stocks, etc.?

A) Ideally, you will want to have up to 3 years’ worth of living expenses in a “safe” investment such as money market CD’s, etc. Typically, a conservative portfolio based on your comfort level of risk. An example might be 20 to 35% stocks, 65 to 80% fixed income.

Q) I am retiring in less than a year, should I continue to put money in my 401 (k)?

A) Yes, especially if you have a company match in your 401 (k).

Q) What if you have a 457? Should I borrow from a 457 before my 401 (k)?

A) While a retirement loan is generally a last resort, the benefit of taking a loan from your 457 is IF you had to leave / separate from service you may not be subject to the 10% penalty (if under age 59 ½)

Q) I have two years until retirement – what is my risk tolerance.

A) Typically, a conservative portfolio based on your comfort level of risk. An example might be 20 to 35% stocks, 65 to 80% fixed income.

Q) If I have a 401 (k) loan should I convert it to a distribution payout? I’m 65.

A) Ideally, no as you will be making it a taxable event.

Market

Q) Is there any benefit to withdrawing large sums of money out of bank accounts during these times ie how do you calm a panicked senior?

A) No. That being said, having a set amount of cash on hand ($ 200 – $ 1,000) for emergency cash transactions is a good practice.

Q) How do you communicate to friends and family members that they shouldn’t be liquidating at this point?

A) First off, it’s maintaining a calmness when talking with them. Going over what their time frame is (when they need the money), recognizing that the investment markets do go down and historically they have rebounded, and finally re-assess their risk tolerance, ie do they need to re-balance their portfolio.

Q) When is the market going to go back up?

A) I wish I knew! Seriously, no one knows that answer, hence sticking to the sound fundamentals of investing and (ideally) dollar-cost averaging into the market.

Q) Once the market stops going down, do you recommend investing in the stock market?

A) Since we do not know when that inflection point will occur, you want to maintain your investment strategy through both the ups and downs of the market.

Q) Is now a good time to purchase stocks?

A) Yes, if you have a long-term investment timeline this could be an excellent time to purchase stocks!

College

Q) Should I keep saving for my child’s education? Or keep it for emergencies?

A) Saving for a child’s education should be behind (1) saving for an emergency (2) saving for your retirement. Also, if there is any high-interest rate debt, that should be prioritized over children’s education.

Q) I have a high school senior going off to college in the fall. I’m concerned about the loss we have recently taken on the money we have set aside for college. Will the market rise soon enough, or should we sell and take a loss?

A) We do not know when the market will rebound. Prior to selling at a loss, consider alternative means, ie student loans that could be paid off once the market does return.

Emergency Fund

Q) What is the correct amount of money for an emergency fund?

A) Start with a goal of $ 1,000 working towards 3 – 6 months’ worth of NECESSARY expenses

Qis it a good idea to hide away money in our home if the market does not recover? Is this what you mean about emergency money?

A) Having emergency cash (think a range of $ 200 – $ 1,000) at home is advisable. Your emergency SAVINGS should be in a safe type of investment (think savings account, CDs, money market accounts).

Buying a Home

Q) I just bought a house this month at what seems to have been the peak of the housing market. Should I be concerned? Or is this a long-term, ride-it-out scenario?

A) Unless you bought the house with the expectation of “flipping” it, a home purchase is a long-term investment

Q) I’m saving up a down payment for a house, now that the stock market is plummeting, I want to invest some money in the market while prices are low, how should I prioritize this?

A) It depends on which goal is MOST important to you. If buying a home is, then saving in a savings/money market account is the preferred way to save. If buying a home is a “nice to do, but can wait” then investing in the market can be beneficial when prices are low.

Q) Hi, we have been preparing to buy a house in an area, that is always high demand and expensive and it will stay that way during the crisis too. Should we buy or wait if something good comes up?

A) With mortgage rates at historical lows, it may still be a great time to buy a home, but you’ll want to consider your job stability.

Q) I am currently in a transition, should I purchase a home or continue to lease/rent?

A) Mortgage rates are at historical lows, so you should consider job stability and how long you plan to stay in the area before making the decision.

Q) If possible, would this be a good time to refinance a mortgage?

A) Yes! Mortgage rates are at historical lows.

Student Loan

Q) How should you think about federal student loans now that interest rates are waived?

A) If you can continue to make your normal payment, this is a wonderful opportunity to pay down the balance more quickly. If you are having issues making the payment, contact your student loan servicer for a forbearance program.